A Kolkata company that has spent fifty years making the rubber liners inside mining mills just bought the world's grinding-media leader for roughly $1.5 billion, took on close to a billion dollars of debt to do it, and in the process turned a clean, profitable small-cap into something that — on paper, for one quarter — posted a net loss.
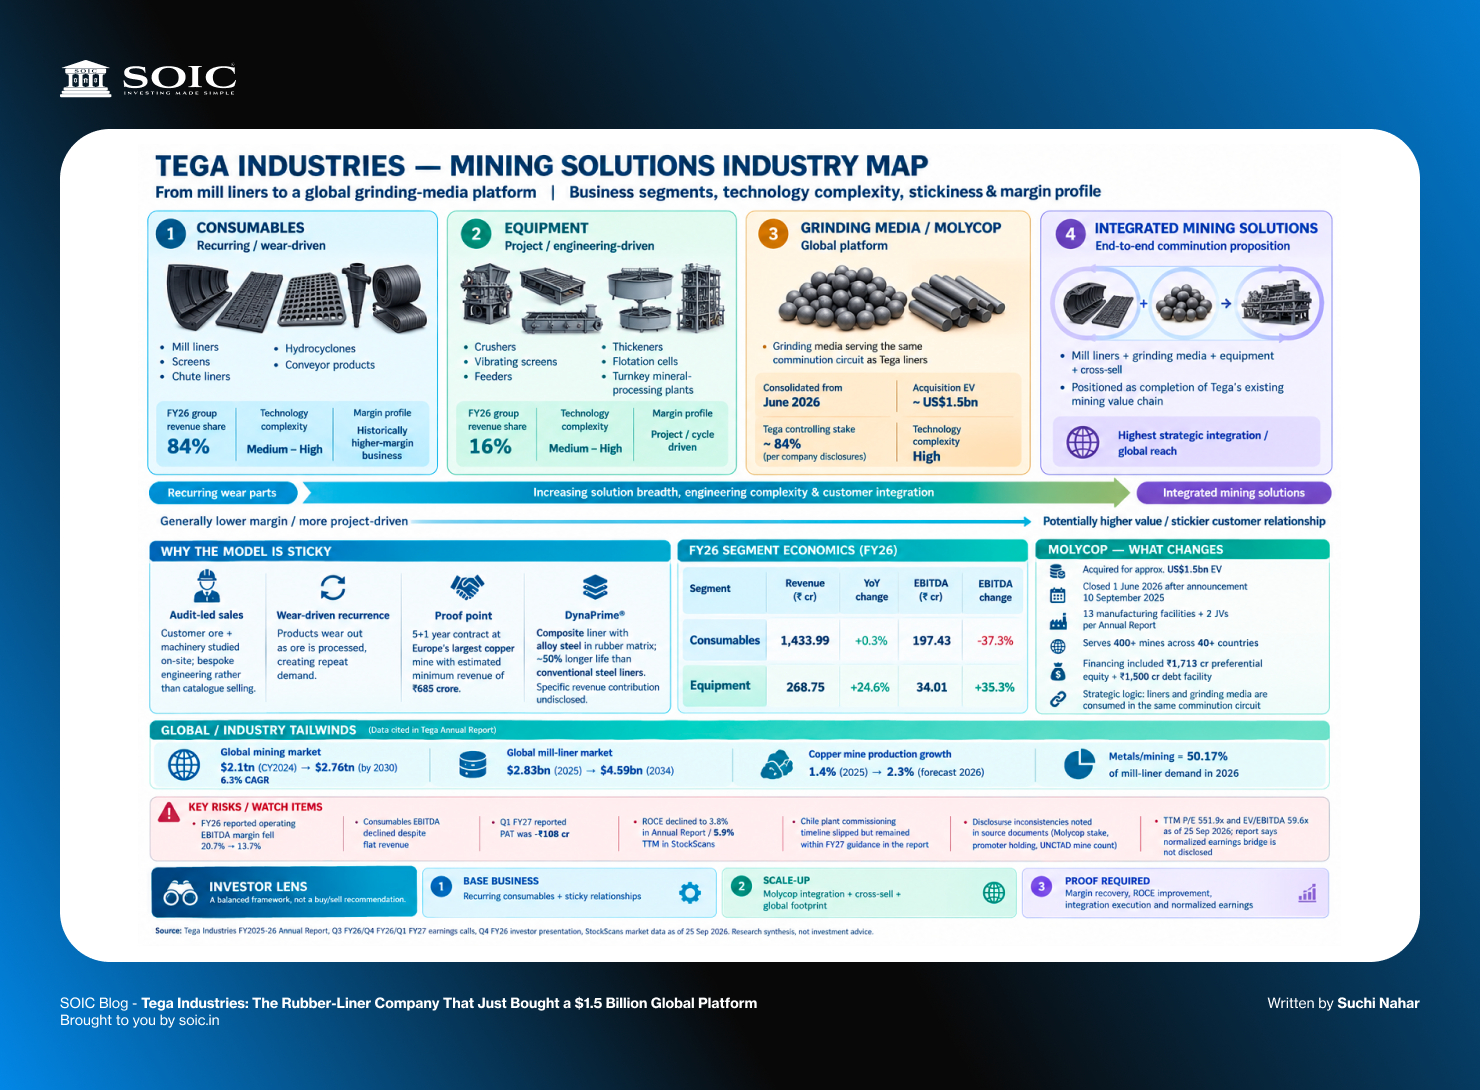
Before the company history and the deal mechanics make sense, it helps to see the whole chain Tega sits inside — from the steel that goes into a grinding ball to the copper that ends up in an EV battery. Six links, in order.
1. Raw materials: The inputs are unglamorous and cost-sensitive: steel bar and billet (for grinding media), rubber compounds, polyurethane, alloy steel and ceramics (for liners and screens). This is the one link where the two halves of the new combined company look genuinely different. For Molycop specifically, steel bar procurement isn't a minor line item—its own CFO disclosed on the August 2026 call that bar payments run at roughly 80% of Molycop's total cost of goods sold.
That's an unusually concentrated input exposure, and it's the reason Molycop ties ~85% of its customer contracts to steel-price indices rather than fixed prices—it needs to pass that cost through, not absorb it.
2. Design and engineering: This is where Tega's consumables business actually differentiates itself from a commodity supplier. Rather than selling off-the-shelf parts, Tega's engineers audit a specific customer's ore characteristics and milling equipment on-site and design a bespoke liner or screen configuration for that exact mill.
It's slower and more relationship-intensive than catalogue selling, but it's also why a first order tends to become a locked-in, multi-year relationship rather than a one-time transaction — the ₹685 crore European copper-mine contract mentioned earlier is what that process looks like once it's converted into a signed deal.
3. Manufacturing: Tega's own footprint traces its history: the original Kalyani plant (1978), the Joka facility, and the Dahej SEZ greenfield unit (2013) in India, plus overseas plants added through smaller bolt-on acquisitions in Australia and Chile over the 2010s. Layered on top since 2023 are McNally Sayaji's four legacy equipment factories, and since June 2026, Molycop's 13 manufacturing facilities spread across the copper-rich regions of Latin America, North America, Australasia and (per management) a growing presence in Africa.
A new Chile plant, aimed squarely at the South American copper base, is under construction now — its commissioning date is the one that's slipped across all three earnings calls (see below).
4. Logistics and distribution: This link is more fragile than it sounds, and it showed up as a genuine, recurring problem across the last two quarters. Finished consumables have to move by container ship to mine sites, and Middle East-related shipping disruption in Q4 FY26 specifically delayed vessel connectivity and container availability, leaving roughly ₹50 crore of finished goods sitting undelivered — representing about ₹100 crore of revenue that simply slid into the next quarter. This is also why Tega maintains "alternate plants" in Chile specifically, so a single facility's downtime or a shipping bottleneck doesn't stall revenue recognition entirely.
5. Sales and technical service: Because the product is customer-specific, the sales motion is a technical one — feet-on-the-ground engineers stationed near major mining hubs (management describes operations spanning seven global regions), doing the ore audits mentioned above and providing ongoing on-site support rather than a one-and-done sales call.
This is also the layer where Tega-Molycop cross-selling is supposed to eventually happen: using each other's existing customer relationships and regional sales presence to introduce the other's product line — the thing management says is still a couple of quarters away from actually showing up in the numbers.
6. The customer, and what happens after: The end customer is a mining company — predominantly copper and gold miners for the consumables business specifically (about 75-77% of that segment's revenue), though Tega's broader customer base, per its own disclosures, spans steel, power, cement, iron ore, zinc, aluminium, platinum and aggregates producers too. And what happens to the metal after it leaves the mine matters for the whole chain's growth case: copper increasingly feeds electrification, EV production, grid infrastructure and — per Molycop's own COO — AI-related data-center buildout; gold moves largely into investment demand and central bank reserves rather than industrial use.
Neither of those end markets is something Tega touches directly, but they're the demand pull that determines how much ore gets processed in the first place — which, as established earlier, is the actual thing Tega's revenue is levered to.
Why walk through all six links: the risk in this business doesn't sit in one place — it's spread across the chain. Input-cost risk sits at link 1 (mitigated by pass-through pricing, with a one-to-two-quarter lag). Execution risk sits at links 3 and 4 (the Chile delay, the shipping disruption). Relationship/moat strength sits at links 2 and 5. And the entire thing is ultimately hostage to link 6 — a mining company's own decision to expand, restart, or mothball a mine, which is exactly what pushed Molycop's own FY27 guidance down from an informal 7-8% to a confirmed 3%.
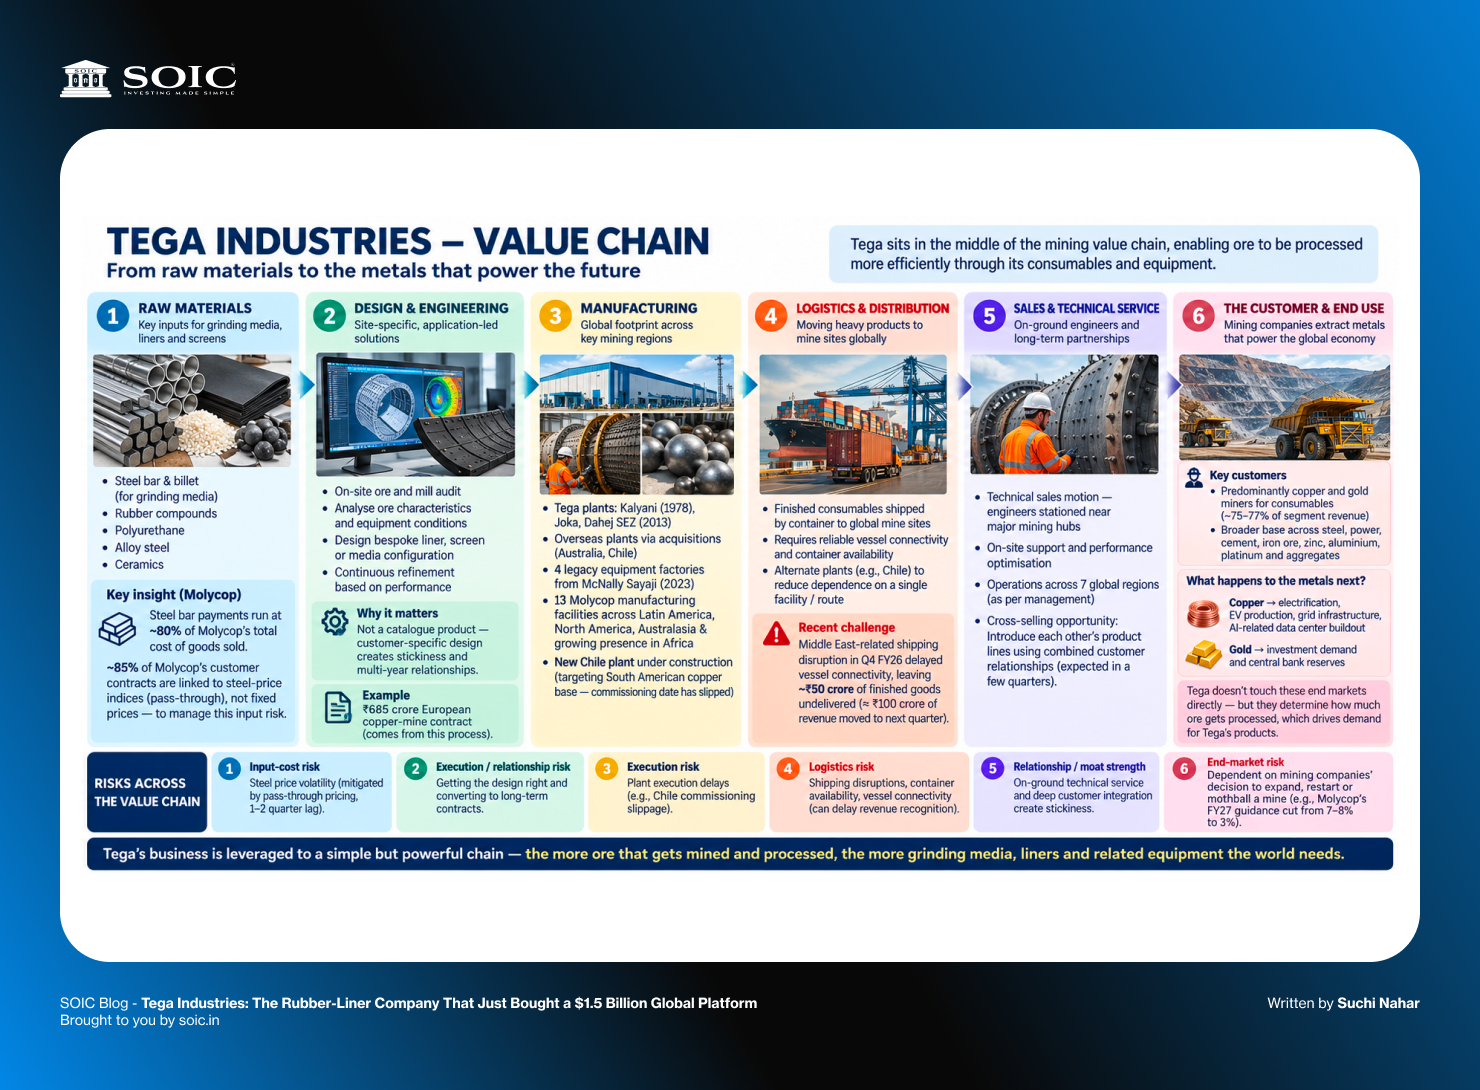
If you've never heard of Tega, that's fair — it doesn't sell anything you'll ever touch. It sells the parts inside the machines that crush rock at a copper or gold mine: liners that protect the mill, screens that sort the ore, and — as of June 2026 — the actual grinding balls that do the crushing.
That last piece is new. For fifty years Tega made the wear parts around the grinding process. In June 2026 it bought Molycop, the company that makes the media doing the grinding itself. It's the equivalent of the company that makes brake pads buying the company that makes the brakes — same car, same customer, but suddenly a much bigger part of the bill.
That's the acquisition. What makes it worth a full read is that the three quarterly calls covering the deal—announcement, close, and first integration quarter — tell a more complicated story than the press release did.
The global mill-liner market is sized at roughly $2.83 billion today, heading to $4.59 billion by 2034 — call it 6% annual growth, unglamorous but real.
The thing worth understanding about this business model: it's a throughput story, not a commodity-price story. Tega's own CFO put it well on the February call — when prices are high, mines that weren't profitable before come back online, more ore gets processed, and that's what drives consumable sales, not the gold price directly. It's a second-derivative bet on mining activity, which is a more defensible position than a straight commodity play, but it also means you can't just chart the gold price and call it a proxy for the stock.
Tega was founded in 1976 in Kolkata as a joint venture with Sweden's Skega AB — which is where its original rubber and wear-technology know-how came from. The next four decades were a fairly typical Indian industrial-manufacturer arc: a Kalyani plant in 1978, an overseas acquisition in 2006, a Dahej SEZ greenfield unit in 2013, an IPO in 2021 that was subscribed 219 times over (third-most-subscribed IPO that year).
2023 — Tega bought McNally Sayaji Engineering out of insolvency. This is a business with roots going back to 1943, and it's now Tega's "Equipment" segment — crushers, screens, beneficiation plants — sold as capital equipment rather than recurring spares. It's the lumpier, cyclical half of the business.
2026 — Tega bought Molycop. This is the transformational one, and it's worth walking through slowly, because the mechanics matter for anyone trying to figure out what happens next.
The Molycop deal:
Molycop is a global grinding-media manufacturer —13 manufacturing facilities, joint ventures on top of that, serving 400+ mines in 40+ countries. Tega announced the deal in September 2025 and closed it on June 1, 2026 — nine months, across anti-trust filings in a dozen-plus jurisdictions, which is genuinely fast for a billion-dollar-plus cross-border transaction. Credit where due: whatever else is debatable about this deal, the execution speed on the legal/regulatory side was real.
The numbers:
Put those together and you get a company that, in the space of one fiscal year, went from a lightly-levered small-cap to one carrying ₹112 billion of group debt (including preference shares) — with management's own stated goal being to bring leverage down to 3x over the next three to four years. That timeline, stated plainly by management itself, tells you this isn't a quick-turnaround story. It's a multi-year deleveraging bet layered on top of a growth bet.
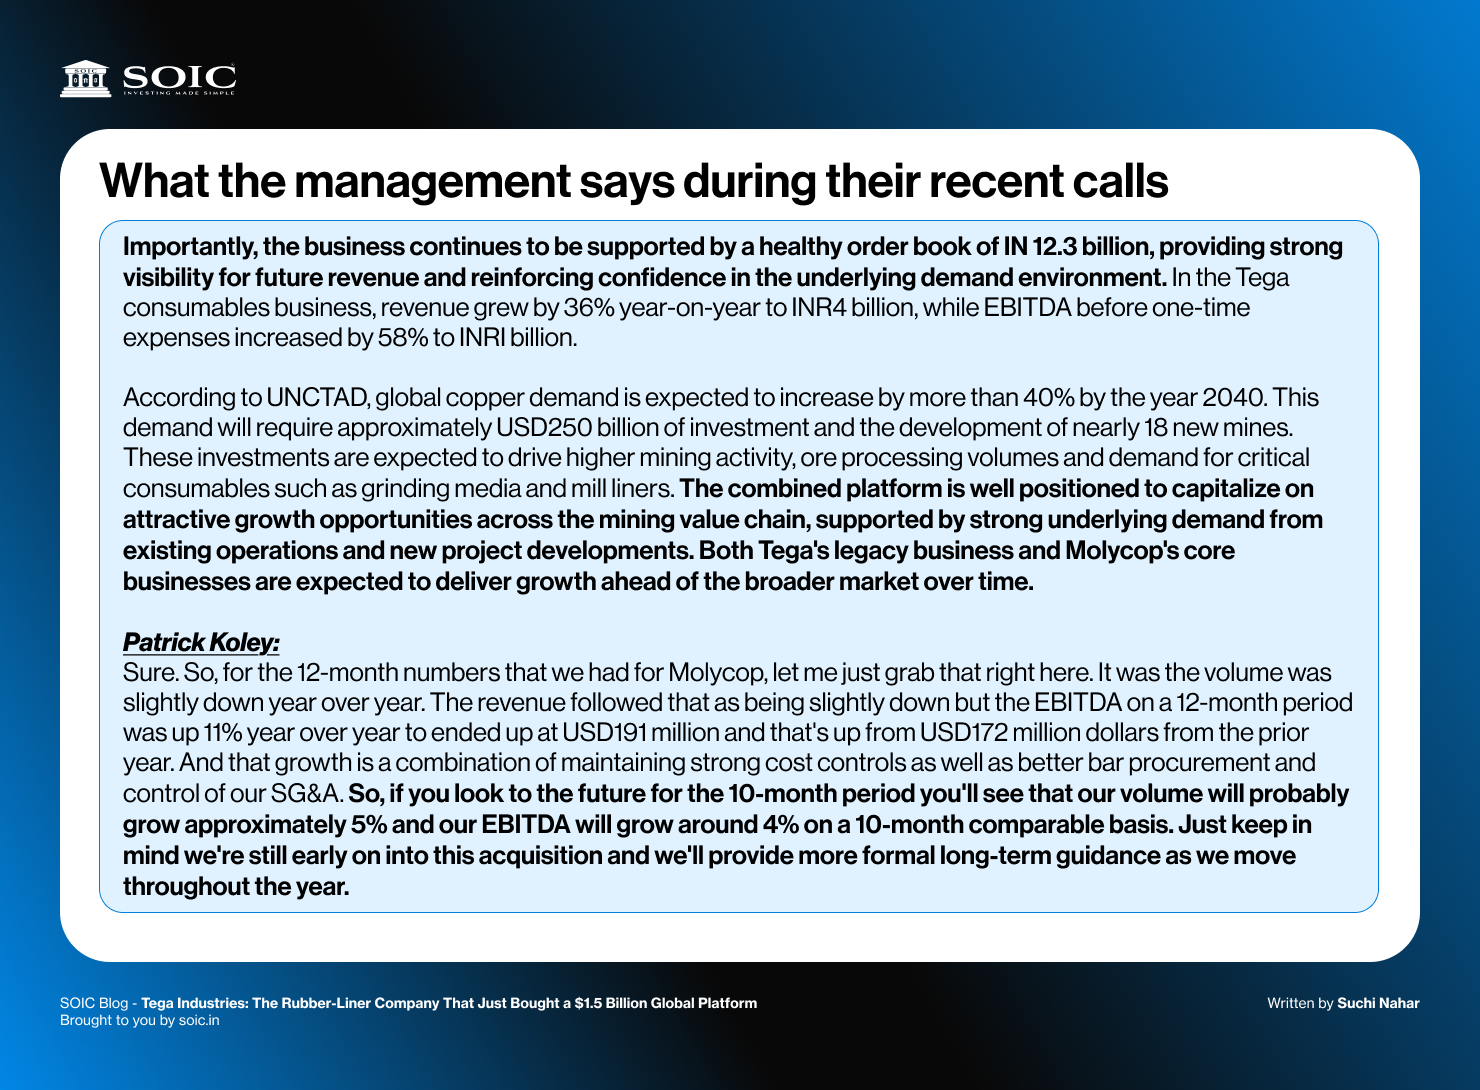
1. The Transformational Move: Molycop Acquisition (~USD 1.5 bn): Management calls this "the most significant strategic development in Tega's history" and "a defining milestone in your Company's journey." Announced September 10, 2025 and completed June 1, 2026 — "in a record nine months" — in consortium with Apollo Funds. Tega holds ~84.2% stake (via Tega HoldCo, upsized by USD 35m to USD 394.3m).
What it brings:
Molycop serves over 400 mines across 40 countries with 13 manufacturing facilities and 2 JVs (US, Canada, LatAm, Australia, Spain, Peru, Mexico, Indonesia, Ivory Coast)
Creates a "comprehensive mill optimisation solution" — Tega's mill liners/screening media + Molycop's market-leading grinding media, process control & analytics → a "unique 'one-stop solution' for mining majors"
Combined footprint: 15 facilities in 9 countries; workforce grew from ~2,900 to over 4,400 employees
Integration priorities (stated by MD & Group CEO):
"Our priorities for the first eight quarters are clear: to combine the complementary strengths..., align capabilities and systems, enhance customer value, support continued innovation and build a platform for sustainable, long-term growth."
Milestones set around Molycop: ~USD 20 million of synergies expected "in the next two to two-and-a-half years" — via optimisation of expenses, SG&A, operational efficiencies, procurement synergies, and leveraging combined scale (Q1 FY27 call)
Dedicated 100-day / 200-day / line-wise integration plans (Q4 FY26 call): Revenue synergies (cross-sell Tega↔Molycop across geographies) expected to ramp from Q3–Q4 FY27 — management wants "a couple of quarters of patience" before giving a definitive number
Deleveraging commitment: bring debt down to ~3x leverage within 3-4 years, aided by divesting non-core/non-productive land parcels (proceeds used to pay down debt; management confirmed these have "no material impact on Molycop's EBITDA"
2. Chile Plant — New Greenfield Manufacturing Facility (FY27 commissioning): Land procured (July 2024): 51,025.77 sqm in Region Concon, Chile for ~INR 21.42 Crore, adjacent to the proposed new plant)
Construction on track: ~50-60% civil work done (Q4 FY26); "construction is going in full swing"
Timeline: "soft commissioning around January 2027 with commercial production starting March" (Q1 FY27 call) — earlier guided Q2 FY27, subject to regulatory approvals (2-month window for local clearances)
Purpose: "required to support our projected growth in Latin America", serving Chile, Peru, Brazil, Argentina
Capex: ~USD 25-30 million(some already spent/borrowed); funded via internal accruals + borrowings
Revenue contribution: management hopeful of 1 quarter of booking in FY27 (possibly end of Q4) or next year
3. Brownfield Capacity Expansion — Multi-Pronged Across Geographies:
From the FY26 Annual Report: Meeting growing customer demand requires continuous investment in manufacturing capability... During FY 2025-26, we advanced a multi-pronged capacity expansion strategy across geographies.
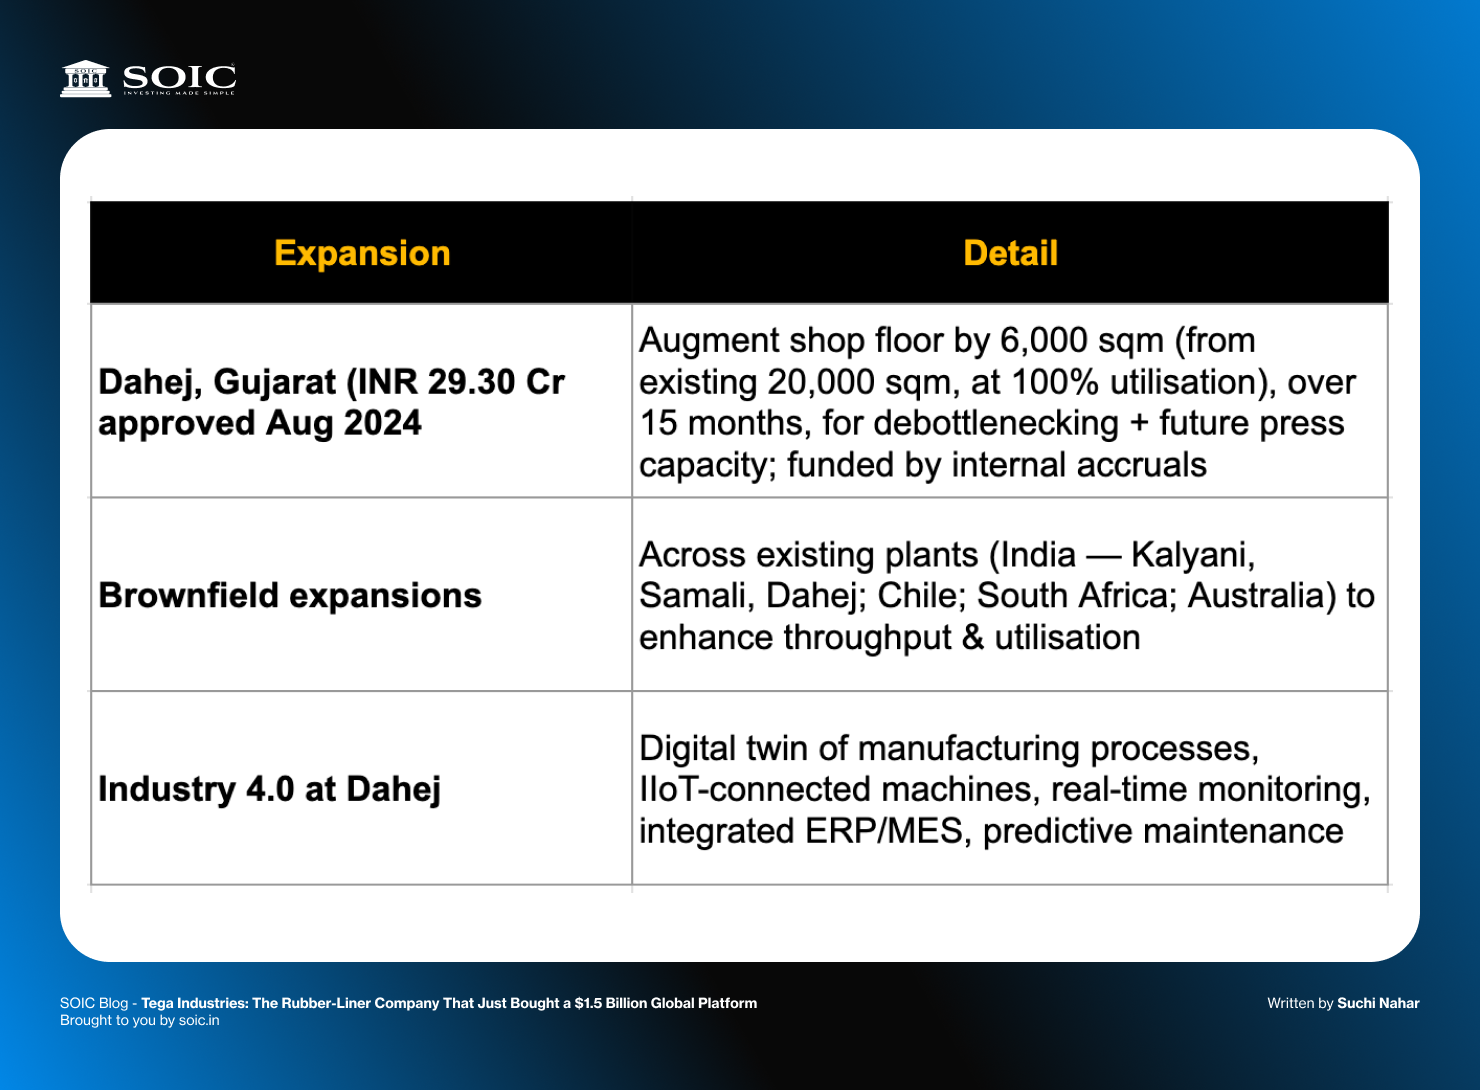
Ongoing focus areas: "Strengthening capacity readiness, improving cost efficiency, advancing innovation-led solutions" — underpinned by TIBEM (Tega Industries Business Excellence Model) and TQM.
4. Equipment Business — New Product Launch & Project Wins
5. New Products, R&D & Digital Innovation (FY26 Annual Report)
R&D spend was ₹67.06 Millionin FY26. Key development streams:
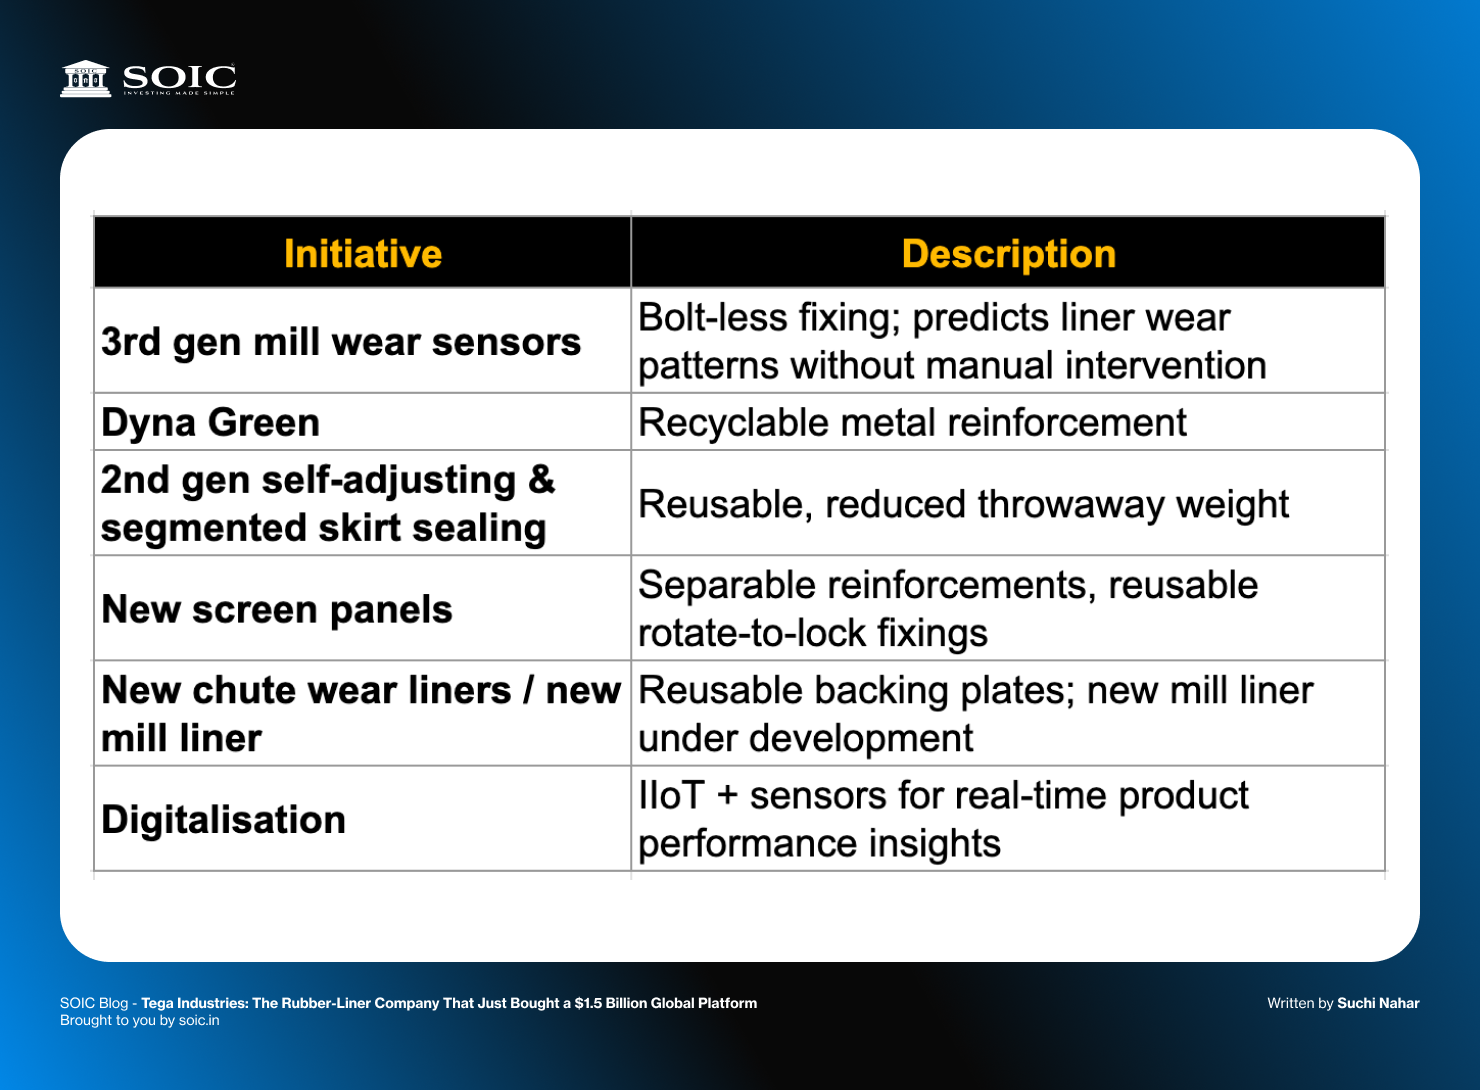
Also exploring Life Cycle Assessments (LCA) and a pilot-scale end-of-life mill liner recovery facility (separating/recovering rubber & metal).
6. Corporate Structuring & New Subsidiaries:
Tega Solutions Limited — new wholly-owned Indian subsidiary effective April 01, 2026, "in line with strategic business and growth objectives"
A chain of Molycop acquisition SPVs created: Tega MC Investment Pte (Singapore), Tega MC JV Holdings, Tega MC SG Holdings/Investments I/II/III, Tega MC Global Holdings, Tega MC Australia Holdings, Tega MC Canada HoldCo, Tega MC US Inc. )
Voluntary de-registration of Tega Industries Australia Pty Ltd(migrated to Losugen Pty Ltd, June ͏2026)
7. Key Financial Milestones / Guidance (Next 1-3 Years):
Metric Target
8. Sustainability Milestones(SAVE Framework)
GHG: Reduce Scope 1 & 2 emissions 20% by FY 2029-30 (baseline FY 2023-24); SBTi-aligned
Solar: scale rooftop solar to 1 MWp by 2027(587 kWp commissioned at Samali; ~325 tCO₂e avoided/yr)
Water: ~10 lakh litres annual conservation potential (~15 lakh litres achieved in FY26); moving toward water neutrality; ZLD at Dahej; 16 KLD STPs at Samali )
Summary — 1-Year vs 3-Year Focus
Next 12 months (FY27) - Complete Molycop integration (100/200-day plans); Chile plant commissioning (Mar 2027); revenue ramp from cross-sell from Q3–Q4 FY27; Dahej capacity completion; new Japanese-collaboration product launch (Q3); Equipment order conversion (~₹12.3 bn order book, ₹9.6 bn executable in 1 year)
Next 3 years (FY28–30) - Deliver USD 20m synergies; deleverage to ~3x within 3-4 years; Molycop mine-restart volume recovery (Cobre Panama, Grasberg — deferred to FY28); brownfield expansions across plants; achieve 20% GHG reduction by FY30; scale combined platform toward 15%+ consumables CAGR
Key caveat noted from management: FY27 consolidated numbers include only one month of Molycop (June 2026) and are provisional (goodwill of ~₹50 bn under IND-AS 103, subject to purchase-price allocation finalisation within one year). Management also cautioned: timing of the Chile commercial production is subject to local regulatory approvals, and cross-sell synergy quantification will firm up "over the coming quarters."
Consumables (about 84% of pre-Molycop revenue). Mill liners, screens, the flagship DynaPrime® composite liner — competing in a global market sized around $900 million to $1 billion with, per management, little direct like-for-like competition.
The business model is audit-led: Tega's engineers study a customer's specific ore and machinery and design a bespoke part, which is what turns a first order into a multi-year relationship rather than a one-off sale. The best evidence of that stickiness: a five-plus-one-year contract at Europe's largest copper mine, with minimum guaranteed revenue of ₹685 crore over the term. That's a real number, not a sales pitch.
Equipment (about 16%, via Tega McNally Minerals): Crushers, screens, beneficiation plants — capital goods sold into new or expanding processing circuits, which makes this segment genuinely lumpy. It fell 44% year-on-year in the most recent quarter purely on "delayed customer clearances," a phrase that's shown up before. But it's also the one segment where the numbers back up the story: EBITDA grew faster than revenue in FY26 (+35% vs. +25%) — real operating leverage, the cleanest print in the whole company this year.
Molycop (consolidated from June 2026): Grinding media at genuine global scale — over 50% market share in its core operating regions, per its own management. About 85% of its contracts are tied to steel-price indices, which protects gross margin but not revenue from steel-price swings — worth knowing if you're trying to model Molycop's top line as something smooth and predictable. It won't be.
To be fair to management, there are real, specific levers here, not just "synergies" as a buzzword:
None of these are fabricated hopes — they're all specific, named, trackable things.
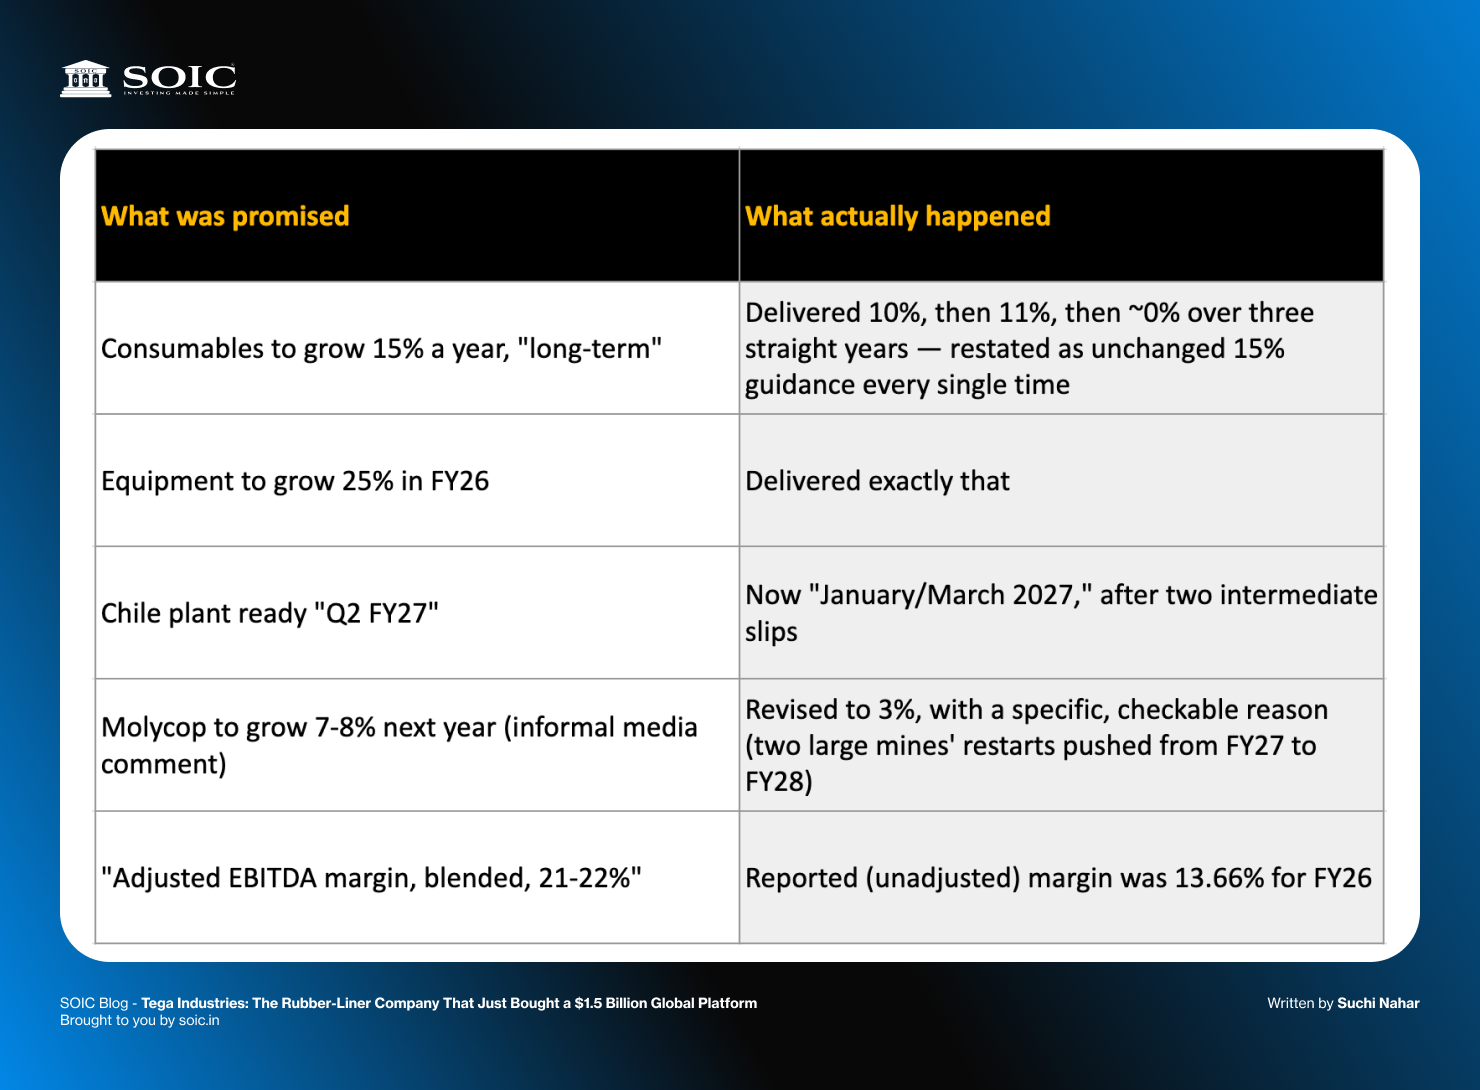
This is the section I think matters most, because you only get to build it after watching the same claims get tested across multiple quarters.
The pattern that emerges: equipment guidance has been reliable, consumables guidance has not been revised despite three years of missing it, and the "adjusted" language consistently makes things look better than the audited numbers do. None of this makes management dishonest — the Molycop explanation, in particular, was specific and verifiable rather than hand-wavy.
But it does mean: treat consumables guidance skeptically, treat capex timelines as directional, and always default to the reported number over the adjusted one.
Bull case:
Bear case:
This isn't a story about whether Tega is a good or bad company — fifty years of history and an 87x pre-deal multiple suggest the market has long respected the franchise. It's a story about whether management can execute an integration that, based on the numbers disclosed so far, has cost more than it's shown to have earned.
The next two or three quarters matter enormously here, in a way they wouldn't for a steadier business. Watch three specific things: whether consumables segment EBITDA margin recovers toward its historical 22-23% band, whether the Chile plant actually commissions on the newest stated date, and whether Molycop's next guidance revision holds — because the last one only held because management could point to a specific, external, named reason (two mines' restart timing) rather than a vague "cyclicality."
Go back to the opening image for a second. For fifty years, Tega's entire job was to protect something else from wearing out — the mill, the mine's own machinery. It was, by design, the company standing next to the main event, making sure the expensive equipment survived contact with the rock. That's a good business. It's also, by its nature, a business that never gets to capture the full economics of the process it serves.
In June 2026, Tega stopped standing next to the grinding process and bought its way into the middle of it. That's the real story here — not "Indian mid-cap does big M&A," but a company that spent five decades perfecting the art of protecting the crushing process deciding it was time to own it instead.
Comment down your thoughts about this company and let us know. Happy to discuss :)
Disclaimer: The information provided is for educational purposes only and should not be considered investment advice. We are SEBI-registered research analysts.
We believe that investment decisions should be based on personal conviction and not borrowed from external sources. Therefore, we do not assume any liability or responsibility for any investment decisions made based on the information provided in this reference.


0 Comments