Let me tell you about a man who couldn't afford a stall at a trade fair.
This was decades ago, near Malkapur in Maharashtra. A man named Janakilal Agarwal used to collect groundnuts and forest seeds every week, and his wife would grind them at home into crude oils and butters. When he finally had a product he believed in — a fat that could make chocolate more stable — he had no booth, no brochure, no marketing budget. So he did the only thing he could. He carried little samples on his own body and showed up wherever he could find a buyer.
One of the people he eventually met that way was Michele Ferrero. Yes, that Ferrero — the chocolate family. Ferrero tried the fat, liked what it did to the texture and stability of the chocolate, and a relationship began that, remarkably, is still running today, roughly eighty years later, through a company called Manorama Industries.
I'm opening with this story because it captures something important about a much bigger pattern in Indian markets — a pattern investors have been quietly getting rich off for years. I call it the "trash-to-cash" story, though the fancier name is "waste-to-wealth." And once you understand how it works, you start seeing it everywhere.
Here's the basic idea. Some of the best businesses in India don't invent some radical new technology. They take something nobody wants — a waste seed, a used car battery, a scrap tyre, sewage water, a piece of broken electronics — and through years of grinding, unglamorous process knowledge, turn it into something a giant global company will pay a premium for.
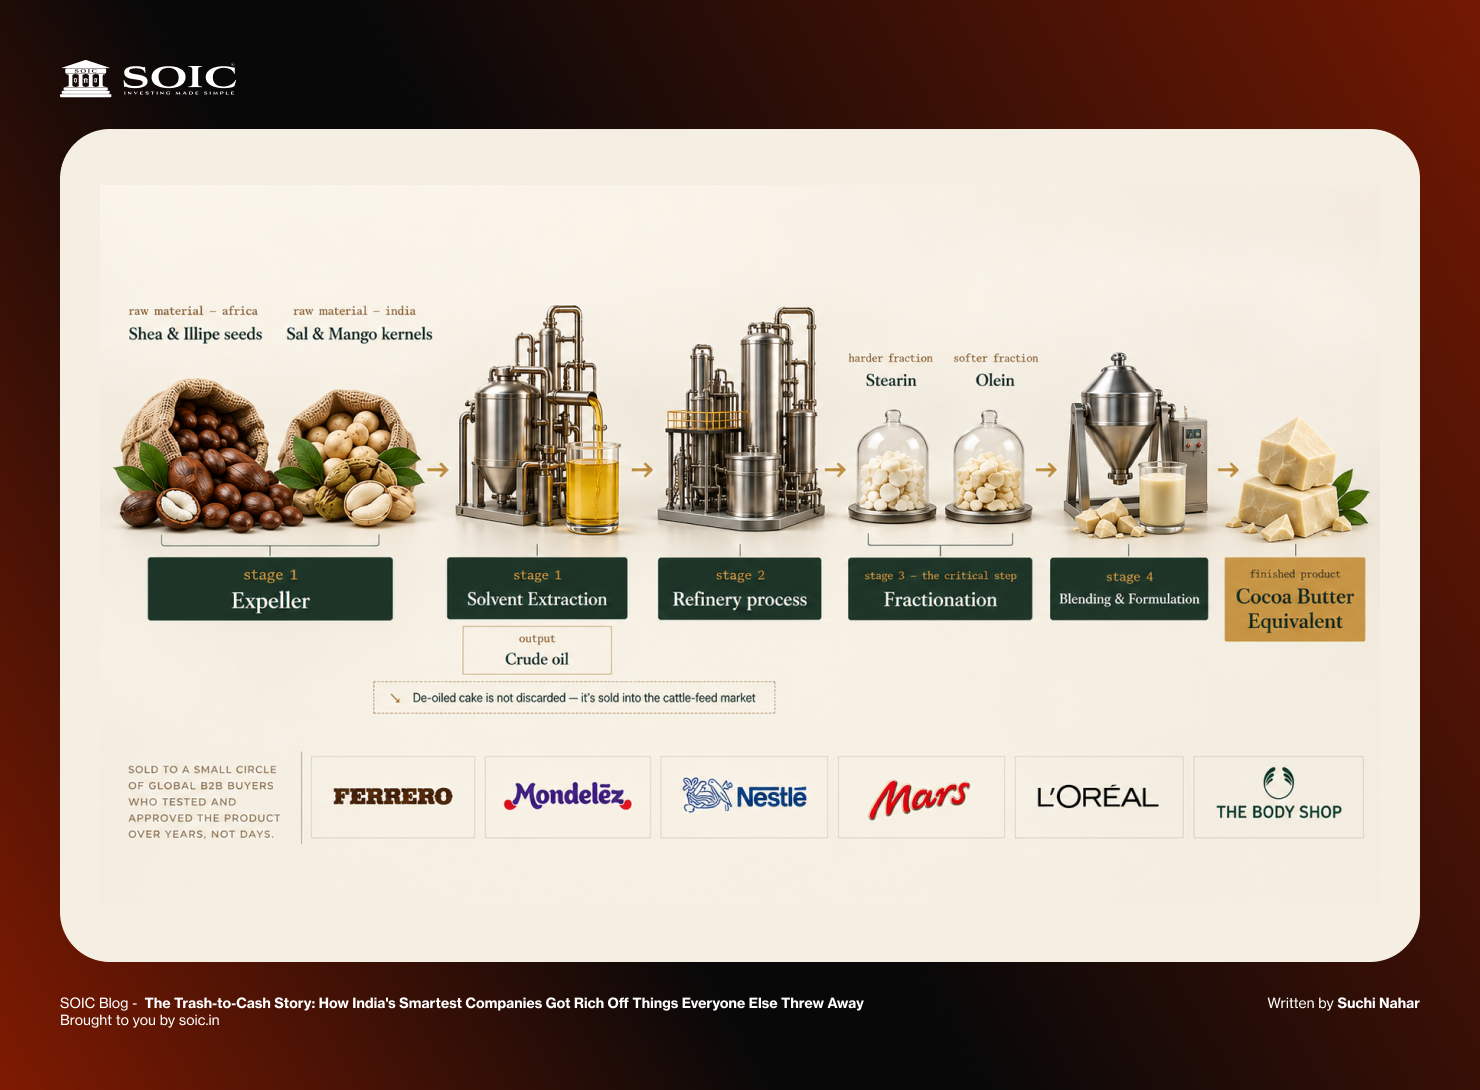
Think about it like this: raw sal seeds falling in an Indian forest are basically worthless. Nobody's fighting over them. But once a company like Manorama collects them, crushes them, extracts the fat, purifies it, and blends it into something that mimics cocoa butter — suddenly Ferrero, Mondelez, Mars, Nestlé, and L'Oréal are queuing up to buy it. Same seed. Completely different value.
Or take a dead car battery. As scrap, it's a lead-acid hazard nobody's excited about. But a company like Gravita or Pondy Oxides Chemicals (POCL) can melt it down, refine the lead, and sell it back into the market as a pure, usable metal — at a fraction of the cost and environmental damage of mining fresh lead ore. Same trash. Completely different value.
This is the whole game: buy cheap, unwanted stuff. Sell expensive, wanted stuff. Pocket the difference — reliably, year after year.
Once you've seen this pattern in Manorama, in Gravita, in POCL, it becomes hard to unsee. And when you line up the businesses that have pulled this off — not just in "waste to wealth" but going back further, to names like CCL Products (turning raw coffee beans into a private-label instant-coffee manufacturing engine), Garware Hi-Tech (turning cheap polyester film into sun-control and paint-protection films), Privi Speciality Chemicals (turning leftover pulp-mill byproducts into aroma chemicals), and Fine Organics (turning ordinary vegetable oil into specialty emulsifiers).
Five things show up again and again, every single time:
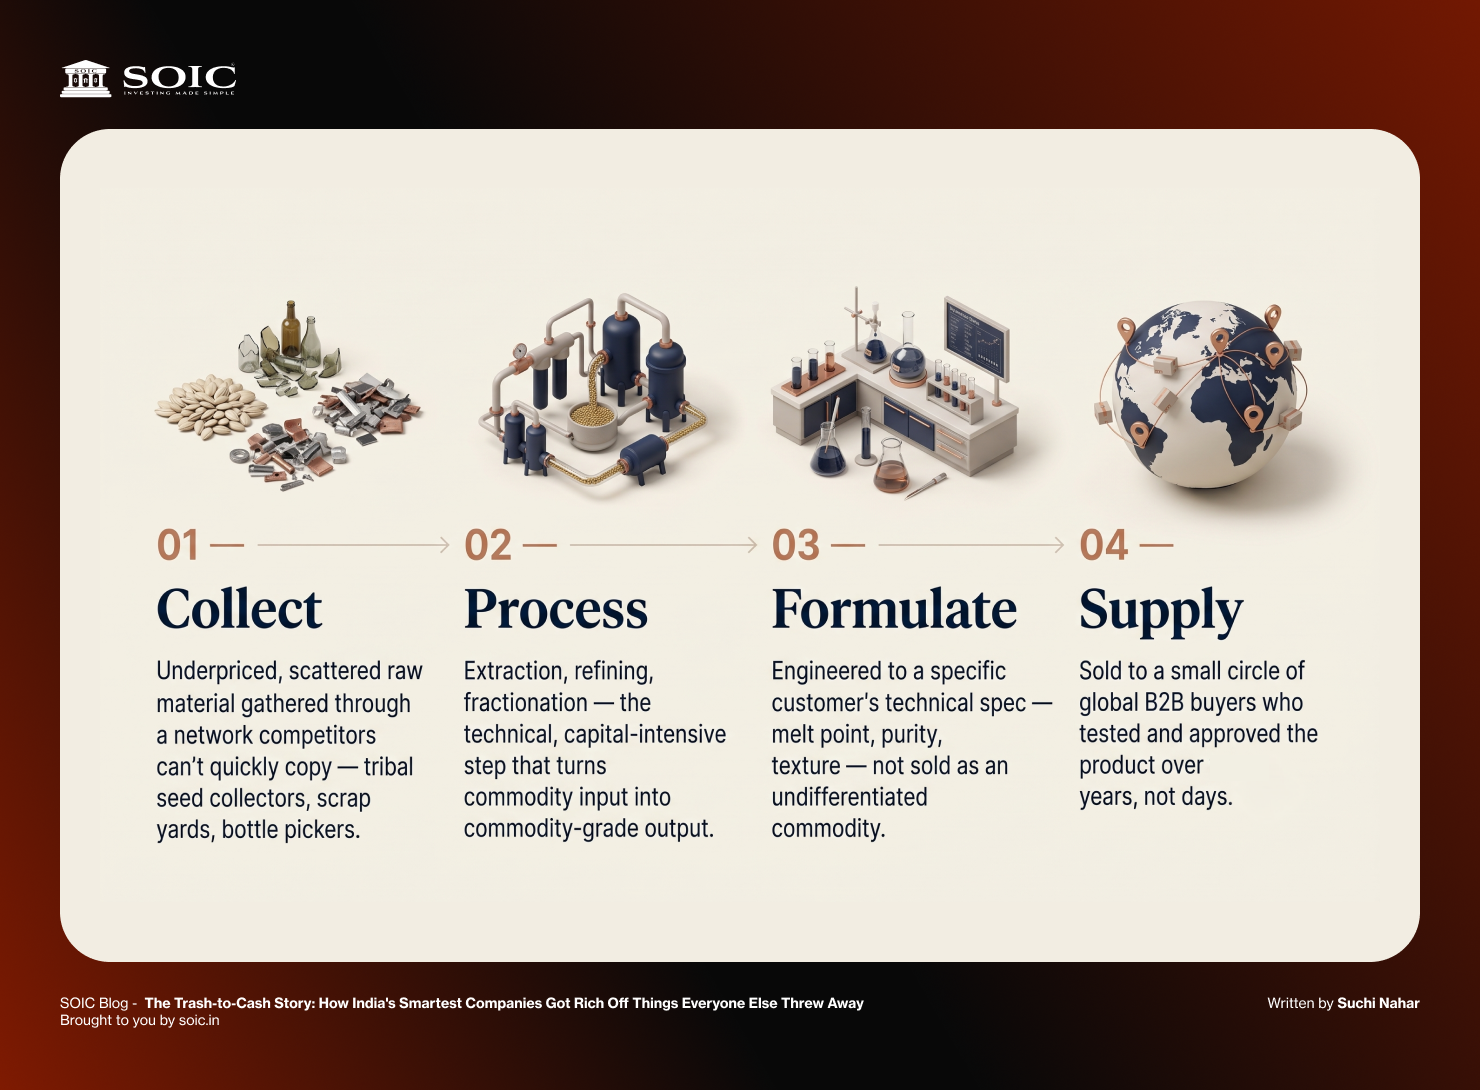
Whether the input is a forest seed, a scrap battery, or a used PET bottle, the value gets created at the same four checkpoints.
The listed waste-to-wealth universe spans seven business models that look superficially similar (“waste in, valuable output out”) but are economically very different — annuity municipal concessions, commodity-spread metal recycling, regulated-demand plastic recycling, tyre valorization, e-waste compliance services, agri-waste technology licensing, and water reclamation EPC/O&M.
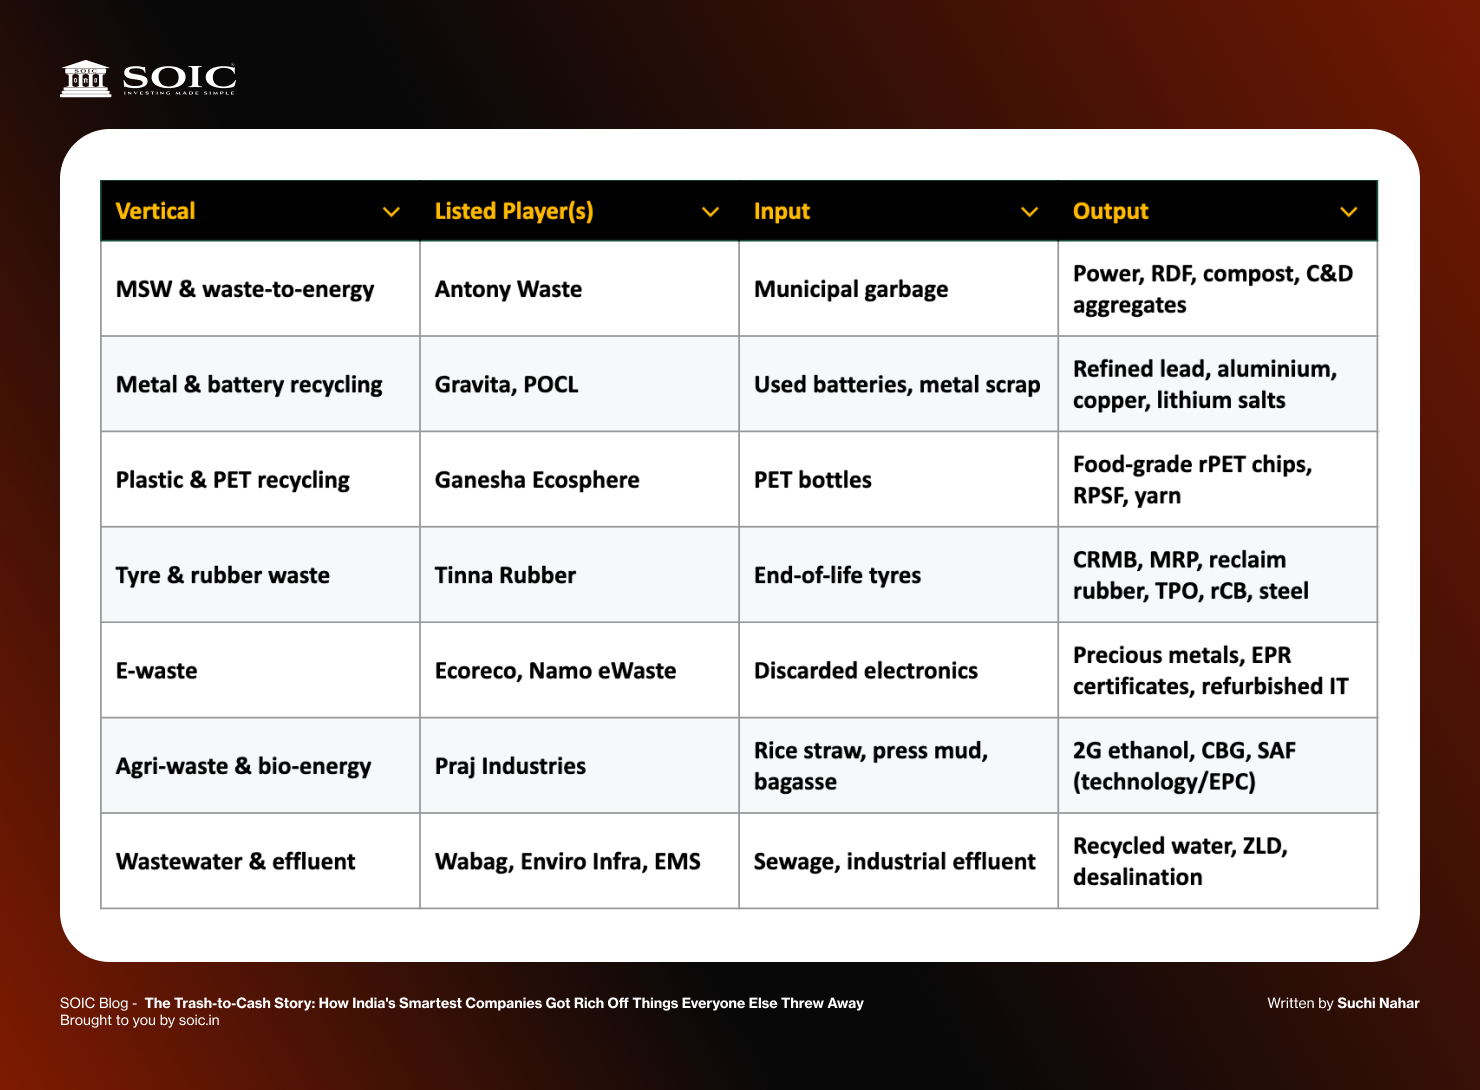
Adjacent but outside this seven-vertical taxonomy: Manorama Industries converts forest seeds (sal, mango, kokum, mowrah, shea) into cocoa-butter equivalents and specialty fats. It is included in this report as a case study because it exhibits the identical economic architecture — cheap/underutilized input, proprietary processing, sticky B2B export customers, stable margins — that defines the broader theme, even though the demand driver is food-ingredient substitution rather than an EPR-style mandate.
Now, you might ask — isn't this just... recycling? Companies have recycled things forever. What makes this special enough that investors pay 30, even 200 times earnings for some of these names?
The answer is margins. Most businesses that touch a commodity get whipsawed by it. If you're a trader buying and selling copper, your fortunes rise and fall with the copper price — you have almost no control over your own destiny. But the best waste-to-wealth companies have found ways to escape that trap entirely.
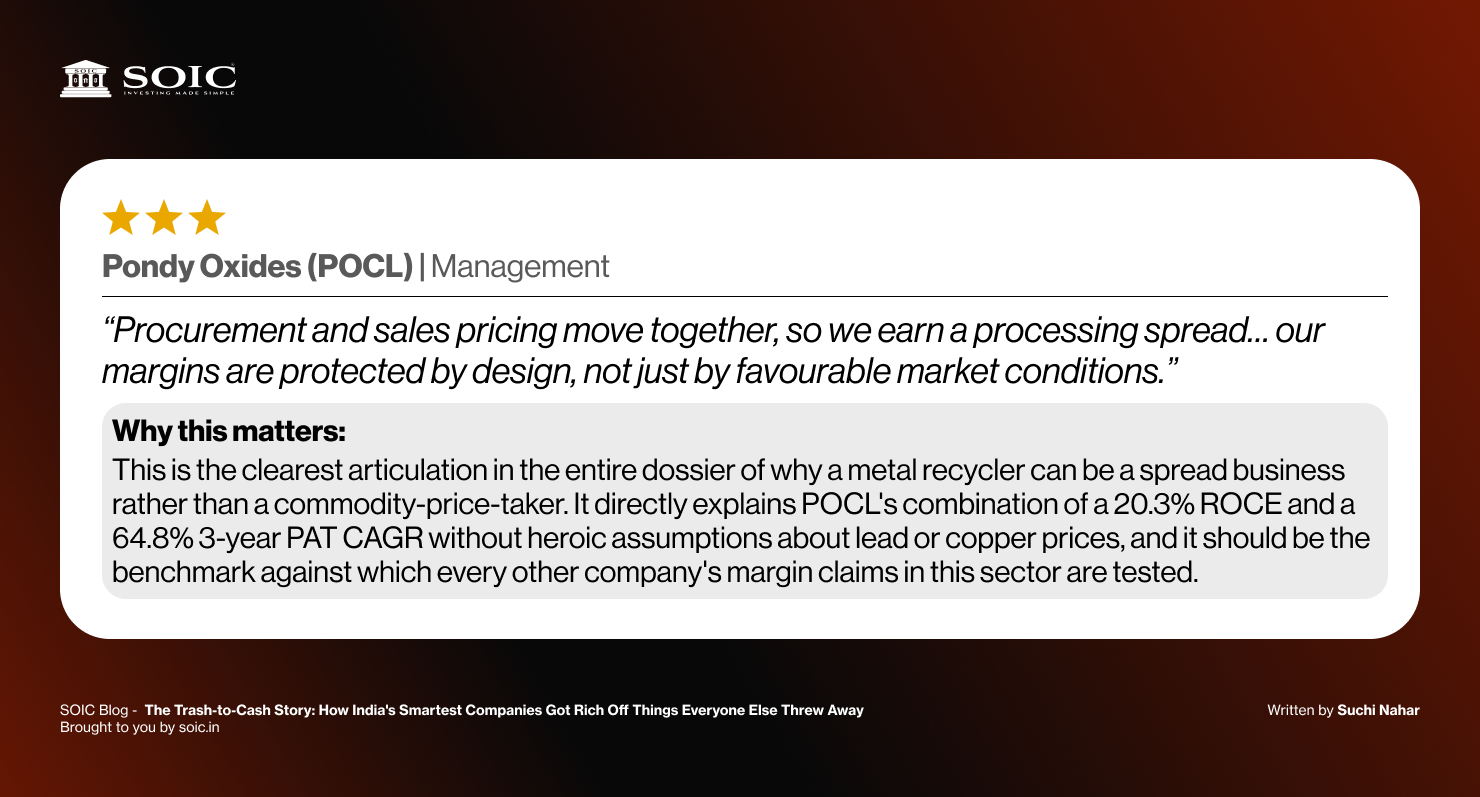
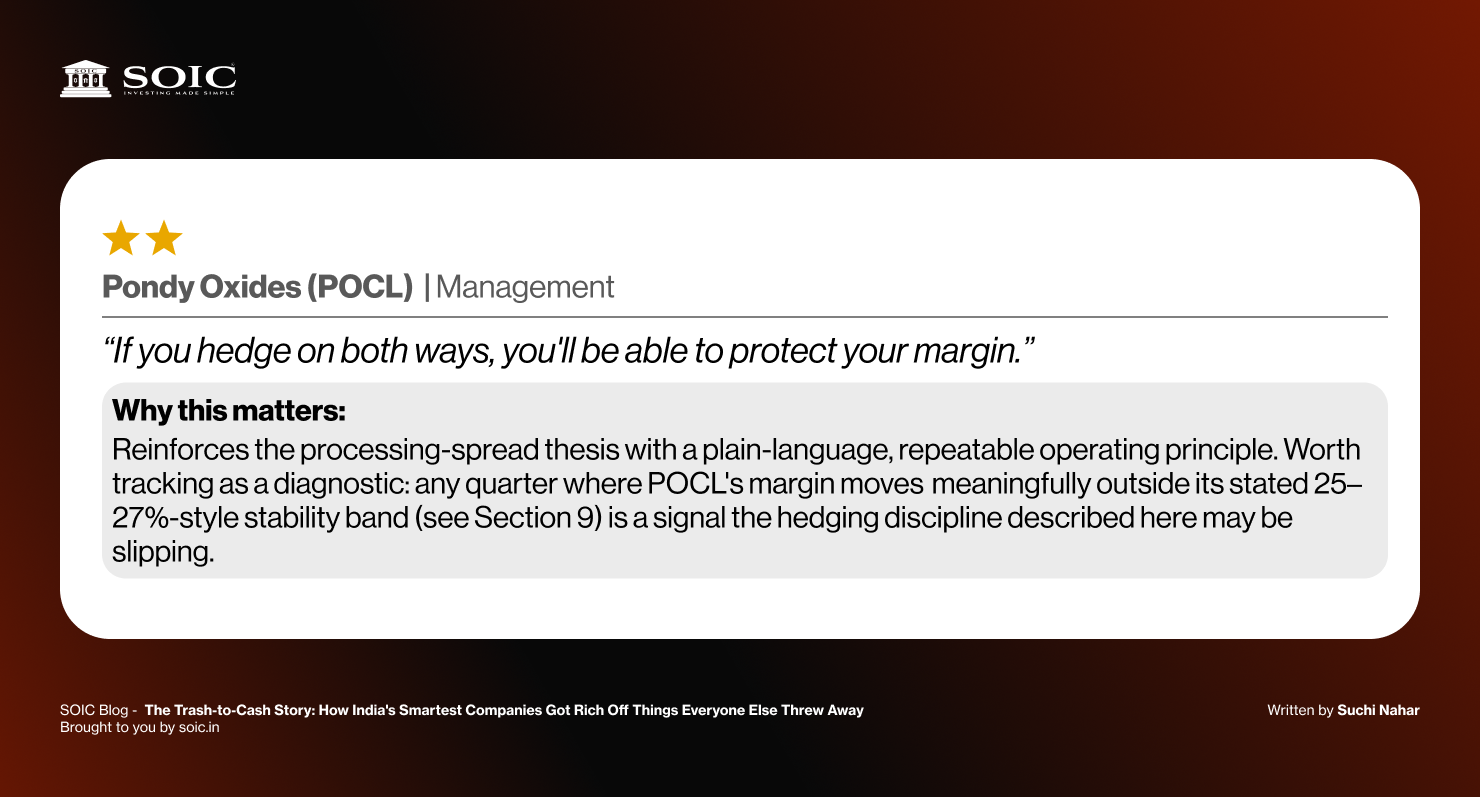
Take POCL. Its management describes its business in a single, elegant sentence: "Procurement and sales pricing move together, so we earn a processing spread... our margins are protected by design, not just by favourable market conditions." In plain English — they don't bet on the price of lead going up or down. They buy scrap and sell refined metal at the same time, locking in a fixed spread in between, like a toll booth that charges the same fee no matter how much traffic is on the road. Whether lead prices soar or crash, POCL still earns its cut.
Gravita does something similar. It hedges its scrap purchases on the same day it buys them, on the London Metal Exchange, so it's never left holding a bag of raw material whose value could collapse before it gets processed. This single habit — same-day hedging — is a big part of why Gravita has managed 15%+ revenue growth and 17%+ profit growth over three years without the wild swings you'd expect from a "metals" business.
Manorama does it a different way — not through hedging, but through pricing power. Its management has been very clear that when cocoa prices rise or fall, it doesn't automatically change how Manorama prices its products. It prices on a cost-plus basis — cost of production, plus a margin, full stop. That discipline is exactly why the company has kept its EBITDA margin sitting steadily around 26% for quarters at a stretch, even while raw material and freight costs bounced around underneath it.
So the real secret isn't "we recycle things." It's "we've built a business where our margin doesn't depend on someone else's commodity cycle." That's a much rarer and much more valuable skill.
Here's something that surprised me when I dug into how these companies actually talk about their own advantages. You'd think the "secret sauce" would be some clever chemical process happening inside the factory. It's not, really. Almost every management team, when pushed, points somewhere else entirely: upstream, to how they *collect* the raw material in the first place.
Manorama runs roughly 18,000 collection centres scattered across India's sal forests, built up through tribal communities over years. Sal seeds only fall for a few weeks each year, they don't grow on tidy plantations you can just drive a truck into, and there's no organized market where you can simply place a bulk order for them the way you would for crude oil. You have to build actual relationships with actual people in actual villages, season after season. That's not something a rival can copy by writing a big cheque. It takes years.
Gravita talks about the same idea from the metal-scrap side — it runs 39 scrap yards and more than 2,200 touchpoints around the world, feeding a constant, reliable stream of raw material into its plants. Ganesha Ecosphere, which recycles plastic bottles into new fibre, has built a network of 300-plus suppliers who bring in roughly 450 tonnes of used PET bottles every single day. Eco Recycling, the e-waste company, is chasing the same goal from a different angle — its stated plan is to eventually run 100,000 collection bins across the country.
None of this sounds exciting. Nobody's writing a magazine cover story about "collection bins." But it's the actual moat. Anyone can build a processing plant if they have enough money. Almost nobody can replicate a decade of trust with tribal seed collectors, or thousands of scrap dealers, overnight.
There's a second force at work here, and it's a big one: government regulation is systematically pushing business away from India's messy, informal "unorganized" sector and toward companies that follow the rules — and the listed companies are the ones set up to benefit.
Consider this: even today, roughly two-thirds of India's lead-recycling capacity is still unorganized — meaning small, unregistered, often unsafe operators. And nearly 85% of India's e-waste is still handled informally, often by people picking apart old phones and computers by hand with none of the safety or environmental controls a listed company has to follow.
That's changing because of rules with names like Extended Producer Responsibility (EPR) and the Battery Waste Management Rules — laws that force the companies who sell products (chocolate bars, batteries, electronics) to prove they're funding proper recycling of what they sell.
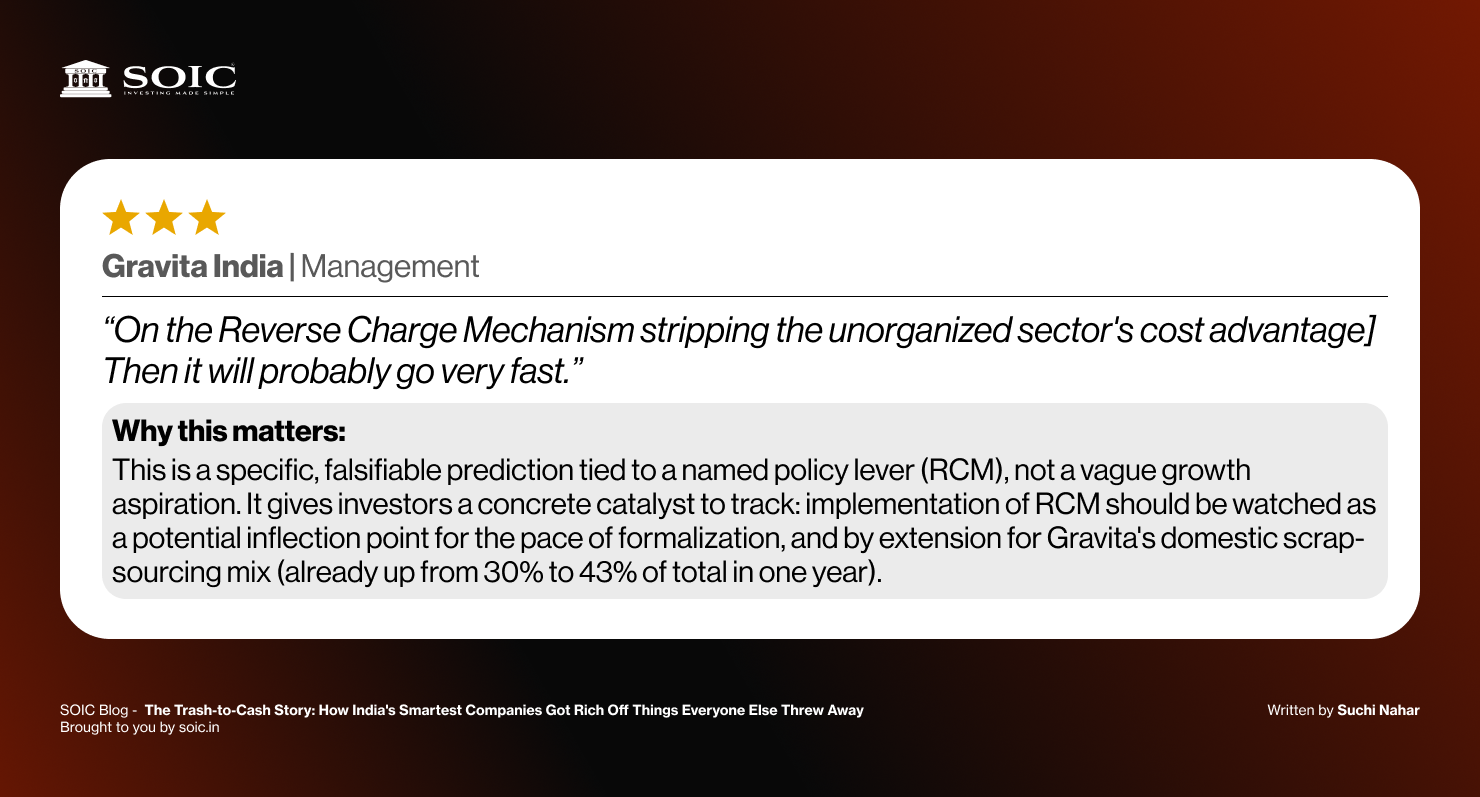
Gravita's management is genuinely excited about one particular rule change here — something called the Reverse Charge Mechanism, which is expected to strip away an 18% cost advantage the unorganized sector currently enjoys. Their prediction, in their own words: once it kicks in, formalization will "probably go very fast."
You can already see the shift happening in the numbers. Gravita's domestic scrap sourcing — meaning scrap bought properly, through organized channels — jumped from 30% of its total in one year to 43% the next. That's not a small move. That's an entire industry's plumbing being rerouted, quarter by quarter.
Here's where it gets interesting, though, because it would be lazy to pretend every company riding this "waste-to-wealth" wave is equally good. Reading through how different management teams actually talk, some real disagreements show up — and they matter a lot if you're trying to figure out which businesses are genuinely special.
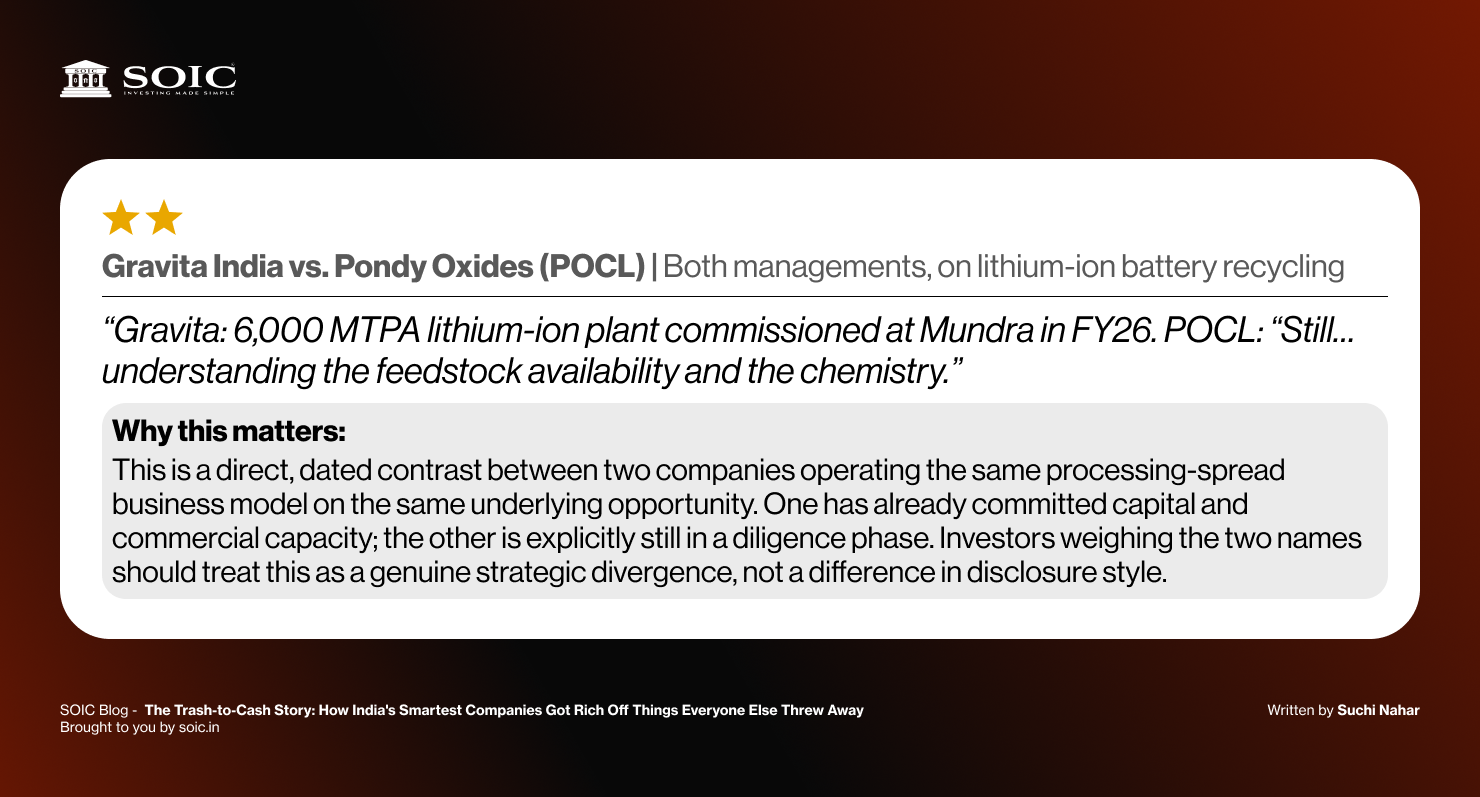
Take lithium-ion battery recycling. It's the obvious next frontier — every electric scooter and phone battery eventually dies and needs recycling. Gravita has already jumped in, commissioning a 6,000-tonne-a-year plant. POCL, working in almost the exact same space, is taking a completely different tone. Its management says it's "still... understanding the feedstock availability and the chemistry" — in other words, they're not ready to commit real money yet. Same opportunity, two very different levels of conviction. That's worth noticing.
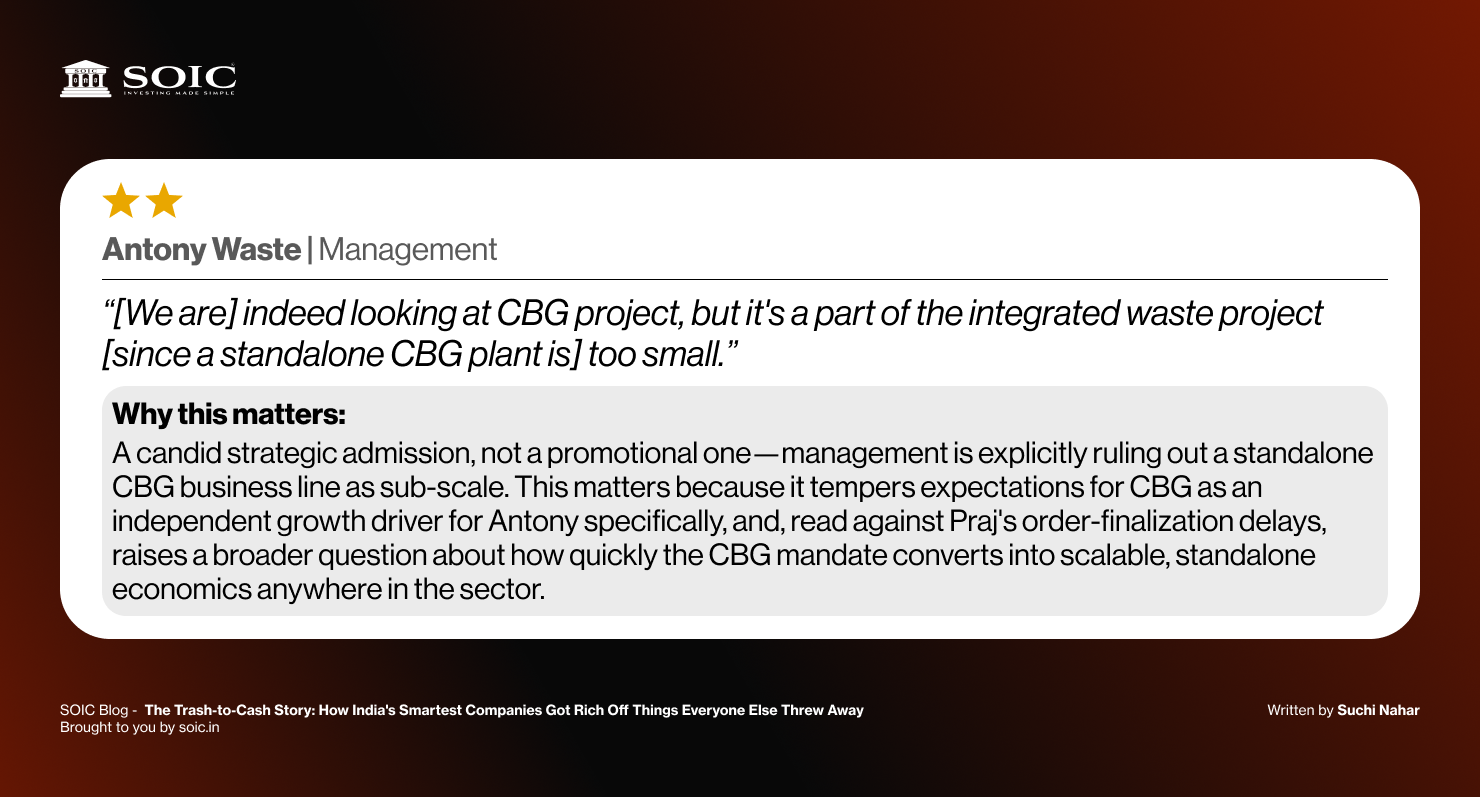
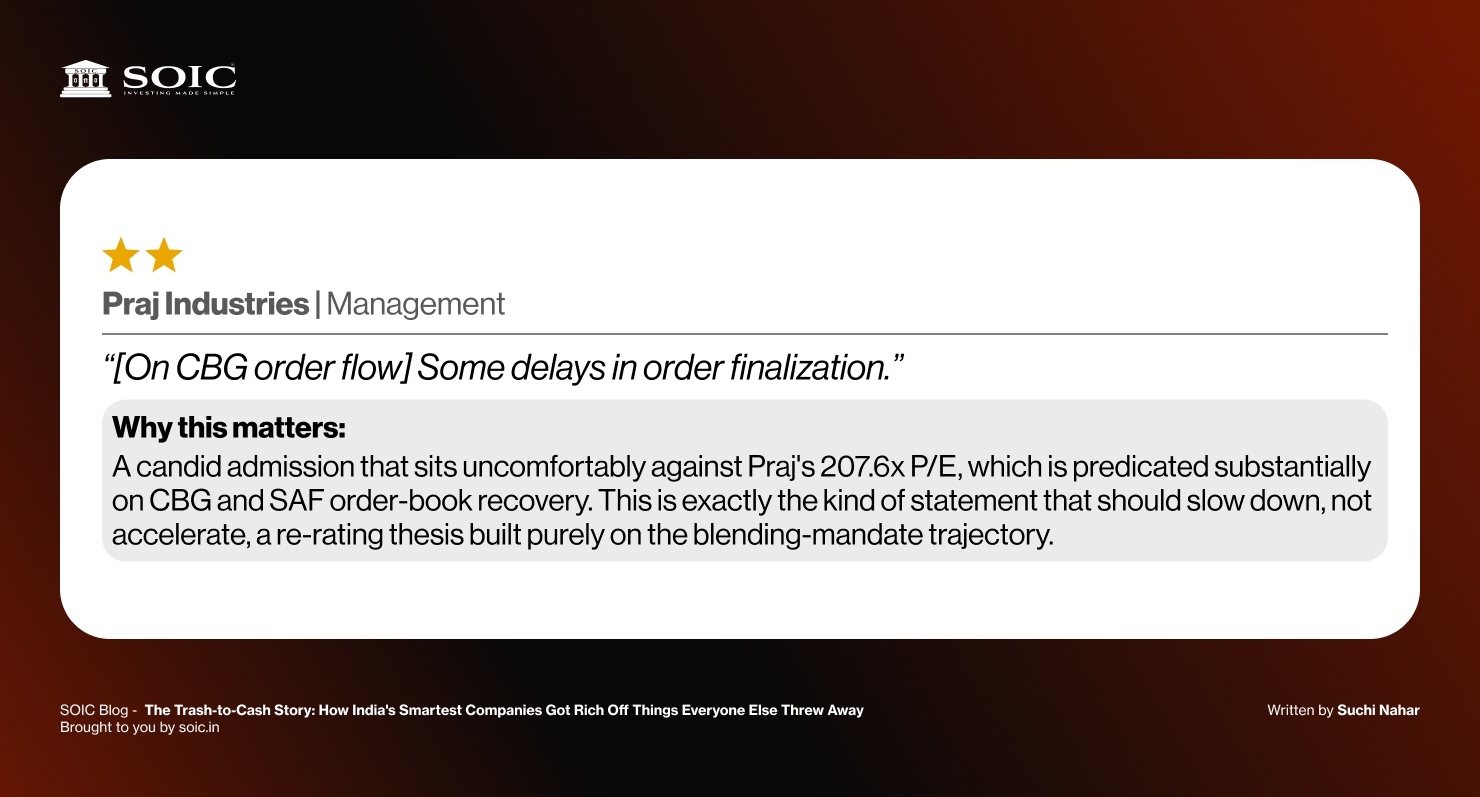
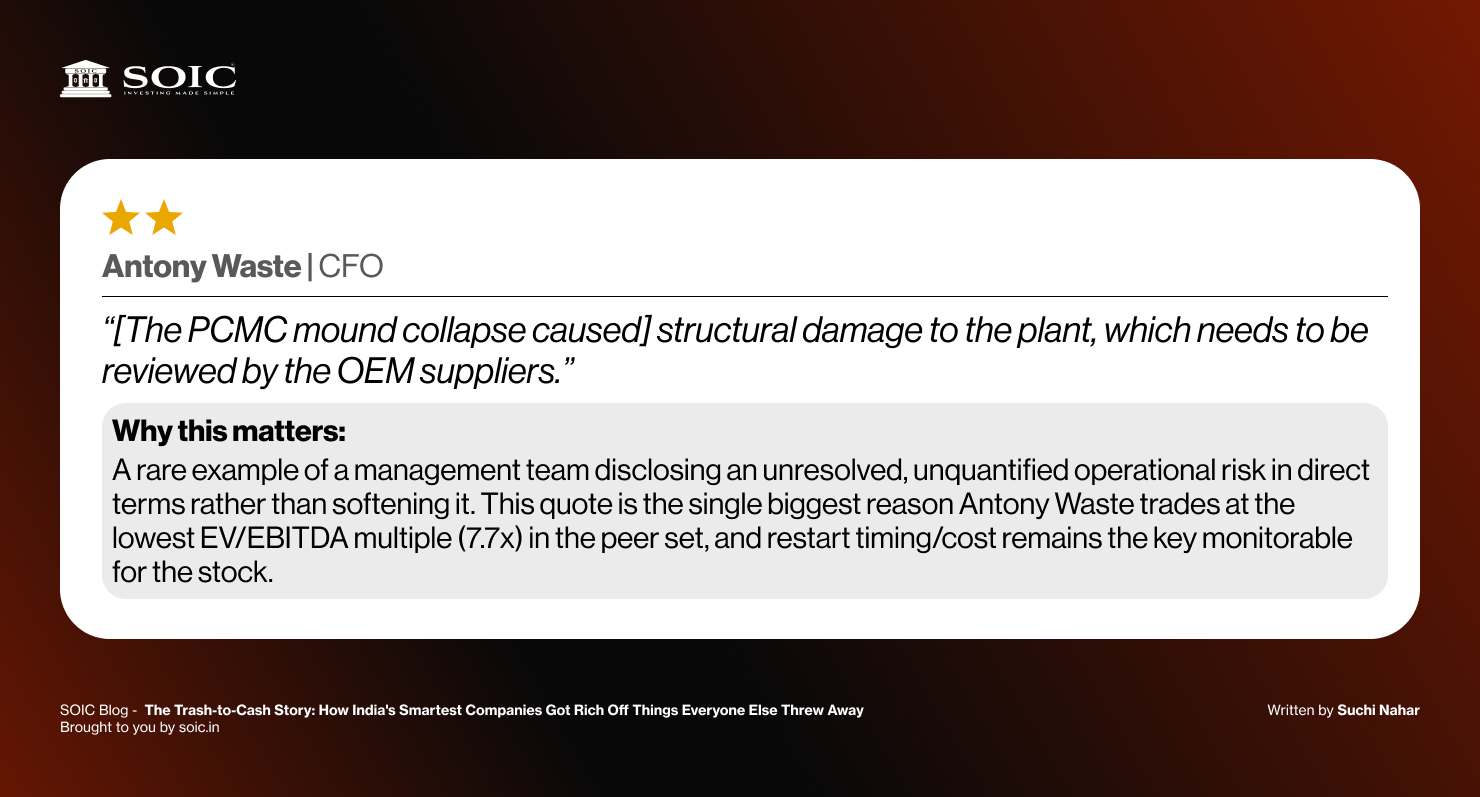
Or take compressed biogas, one of the hottest buzzwords in the waste-to-energy space right now. Praj Industries has built an entire business around licensing biogas technology — more than 40 plants installed. And yet Praj's own management has admitted there have been "some delays in order finalization." Meanwhile, Antony Waste — a company that runs India's garbage-collection contracts — was asked directly whether it plans to build a standalone biogas plant, and its answer was refreshingly blunt: a standalone plant is simply "too small" to bother with on its own; it only makes sense bundled into their existing waste operations.
Put those two comments side by side, and a pattern emerges: the biogas opportunity that looks so exciting on a regulatory chart (rising from 1% to 5% mandatory blending by 2029) might be a lot harder to actually convert into signed, profitable orders than the headline number suggests.
Here's a genuinely important lesson: regulation creating demand is not the same thing as regulation protecting your margin. Ganesha Ecosphere recycles plastic bottles into a product called rPET, which brands are increasingly required to use. Sounds bulletproof, right? Except in one quarter alone, Ganesha's volumes fell by roughly 25% — not because demand disappeared, but because a single government notification let brands delay their purchases for a few years. The rule didn't go away. The timing did. That's the kind of risk you'd never spot just by reading a headline about a "regulatory tailwind."
CL Products — Coffee as a Manufacturing Problem, Not a Commodity Trade
CCL Products (formerly Continental Coffee) took a raw commodity — green coffee beans — and built one of the world's largest private-label instant coffee manufacturing platforms around it. Rather than compete as a coffee trader exposed to bean-price swings, CCL built the processing infrastructure (freeze-dried and spray-dried instant coffee) and R&D capability to become the manufacturing backbone for global retail and QSR brands that don't want to build their own coffee-processing plants. The business model converts a volatile agri-commodity into a contracted, formulation-driven manufacturing relationship — the textbook transition from "seller of a commodity" to "processor with technical stickiness."
Garware Hi-Tech Films — Polyester Film as a Platform, Not a Sheet of Plastic
Garware Hi-Tech starts with polyester film — about as commoditized an industrial input as exists — and, through coating, lamination, and specialized R&D, converts it into products like sun-control window films and paint-protection films (PPF) for the automotive and architectural markets. A roll of BOPET film sells for a fraction of what a branded, warrantied PPF product commands once Garware has engineered UV-resistance, self-healing top coats, and optical clarity into it. The company's export-heavy, brand-distributed PPF business looks nothing like a commodity plastics business anymore, even though the raw material entering the plant is identical to what a basic packaging-film maker uses.
Privi Speciality Chemicals — From Paper-Mill Pulp Byproducts to Aroma Chemicals
Privi takes low-value byproducts of the pulp and paper industry — feedstocks most of the world treats as waste to be disposed of — and, through fractionation and chemical synthesis, produces aroma chemicals used in fragrances, flavors, and personal-care formulations sold by the world's largest fragrance houses. The transformation from "pulp mill residue" to "ingredient in a premium perfume" is about as complete a value-creation journey as this framework describes, and it explains why Privi trades at a premium multiple despite touching agri-industrial waste streams at the start of its chain.
Fine Organics — Vegetable Oil as the Starting Point for Specialty Additives
Fine Organics takes vegetable oils — a global commodity with liquid, transparent pricing — and converts them into specialty oleochemical additives such as emulsifiers, used across food, plastics, cosmetics, and polymer processing. These additives are dosed in tiny quantities but are functionally critical to the end product's performance (texture, shelf life, processability), which is exactly why Fine Organics can price on a cost-plus basis rather than a commodity spread, and why its customer base — spanning food and plastics majors globally — has stayed remarkably sticky.
What ties these four together is not the industry (coffee, plastics, chemicals, oleochemicals are unrelated on paper) but the economic architecture: cheap, volatile input → proprietary processing → technical, sticky, export-oriented B2B output → stable, premium margins.
Widening the Lens: The New Wave of Waste-to-Wealth Businesses
Over the last few years, a second, distinct cluster of "waste-to-wealth" businesses has emerged on Indian exchanges — this time built explicitly around regulatory-driven circular-economy demand (Extended Producer Responsibility, Battery Waste Management Rules, mandatory recycled-content norms) rather than pure product innovation. It's worth mapping this cluster against the same five-point framework, because it shows both how far the pattern extends and where it starts to bend.
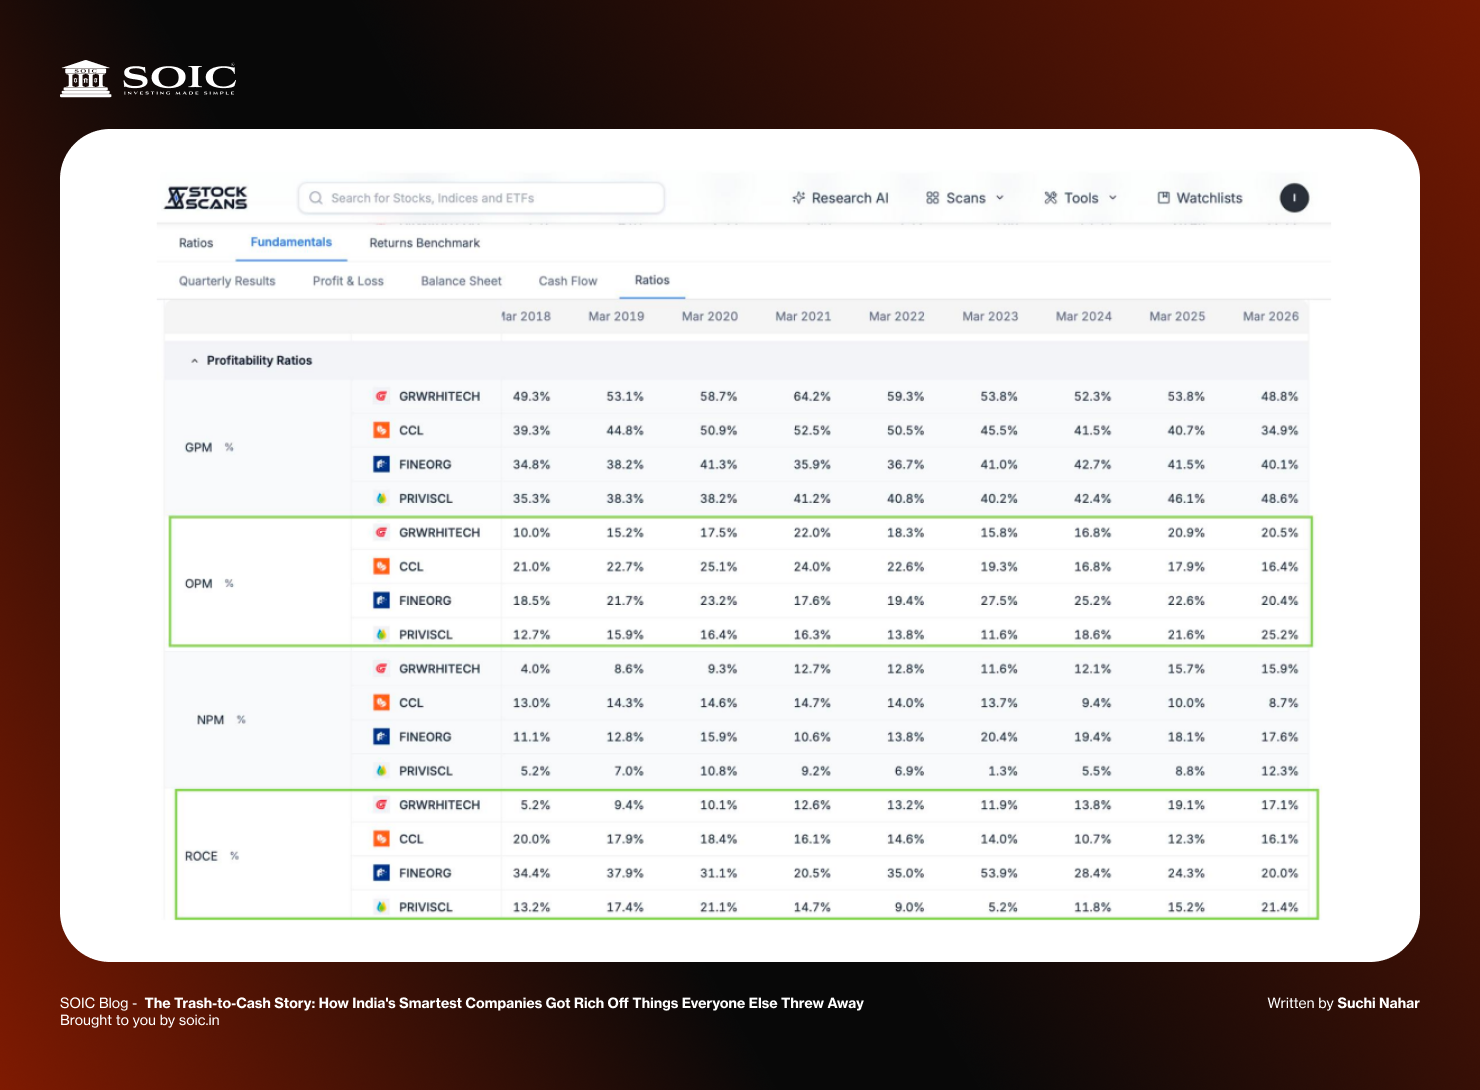
The margin profile of these businesses is the ultimate proof of their strategy. While a company merely trading repriced commodities typically struggles to maintain single-digit margins during market downturns, these players operate on a completely different level. Consider the numbers: Manorama has consistently preserved its EBITDA margin near 26% despite severe fluctuations in raw material and freight costs.
Similarly, Fine Organics and Privi have historically delivered gross margins between 30% and 40%+, alongside robust double-digit operating margins. This financial performance reflects that of a high-value specialty-chemicals enterprise rather than a traditional oil-presser or seed-crusher. Such enduring profitability is by design—it represents the core investment thesis hiding in plain sight.
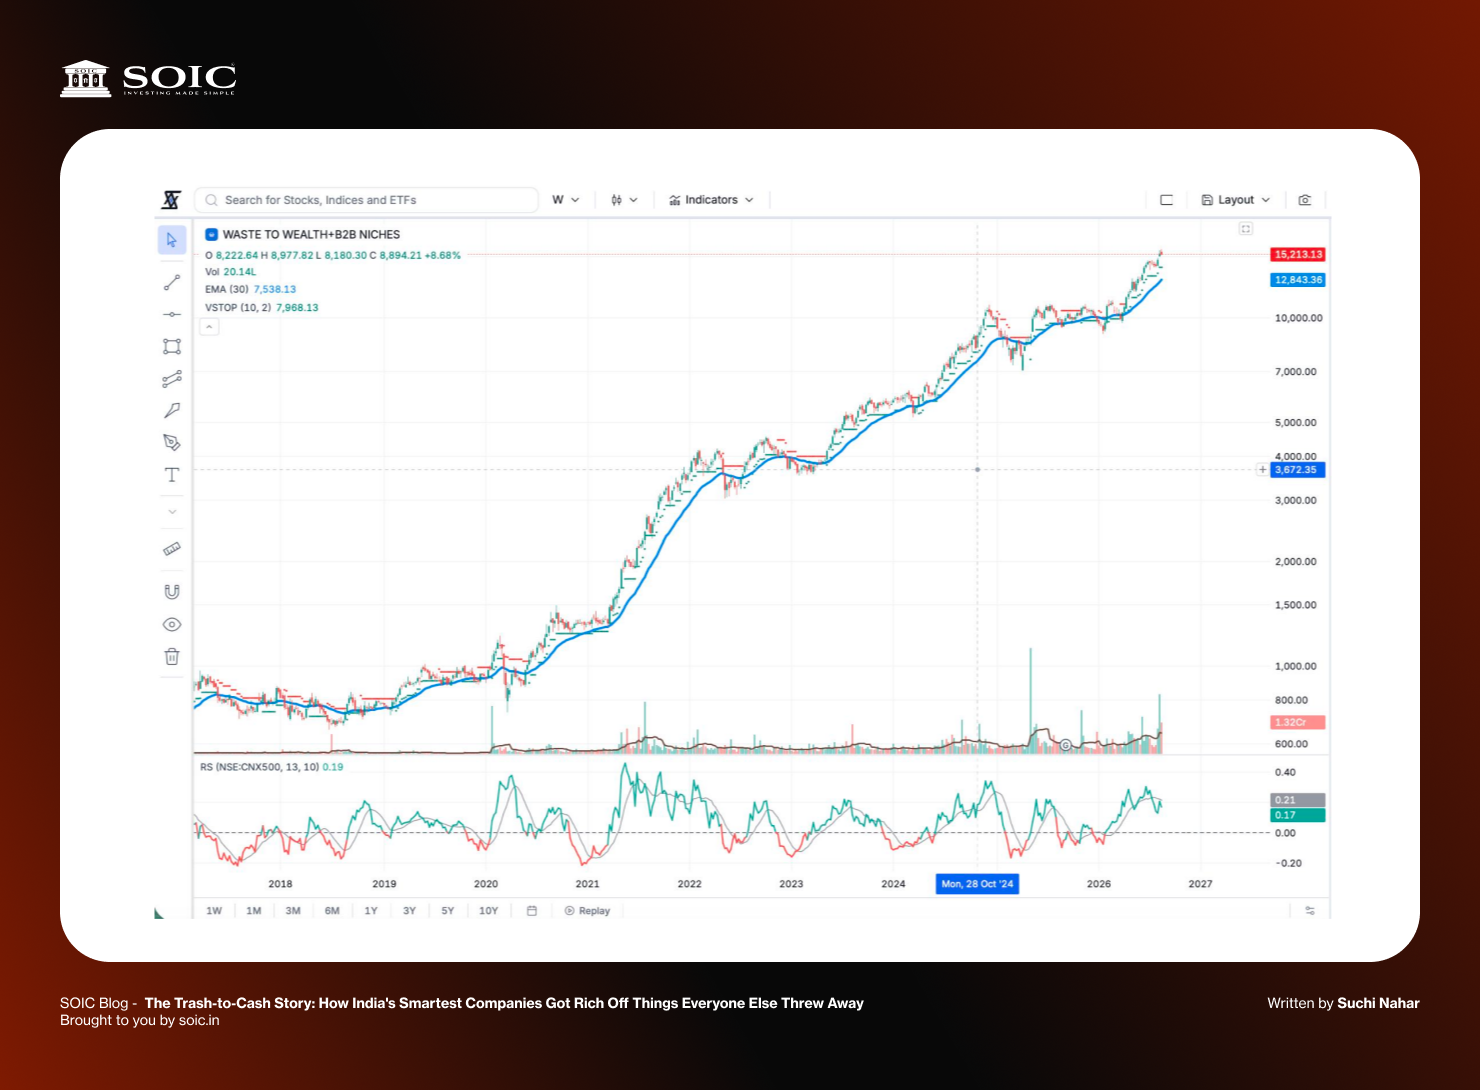
The honest takeaway from this is : not every business that touches "waste" earns the same quality of franchise. The recyclers with hedged, spread-based pricing (Gravita, POCL) come closest to replicating the margin stability of the classical playbook.
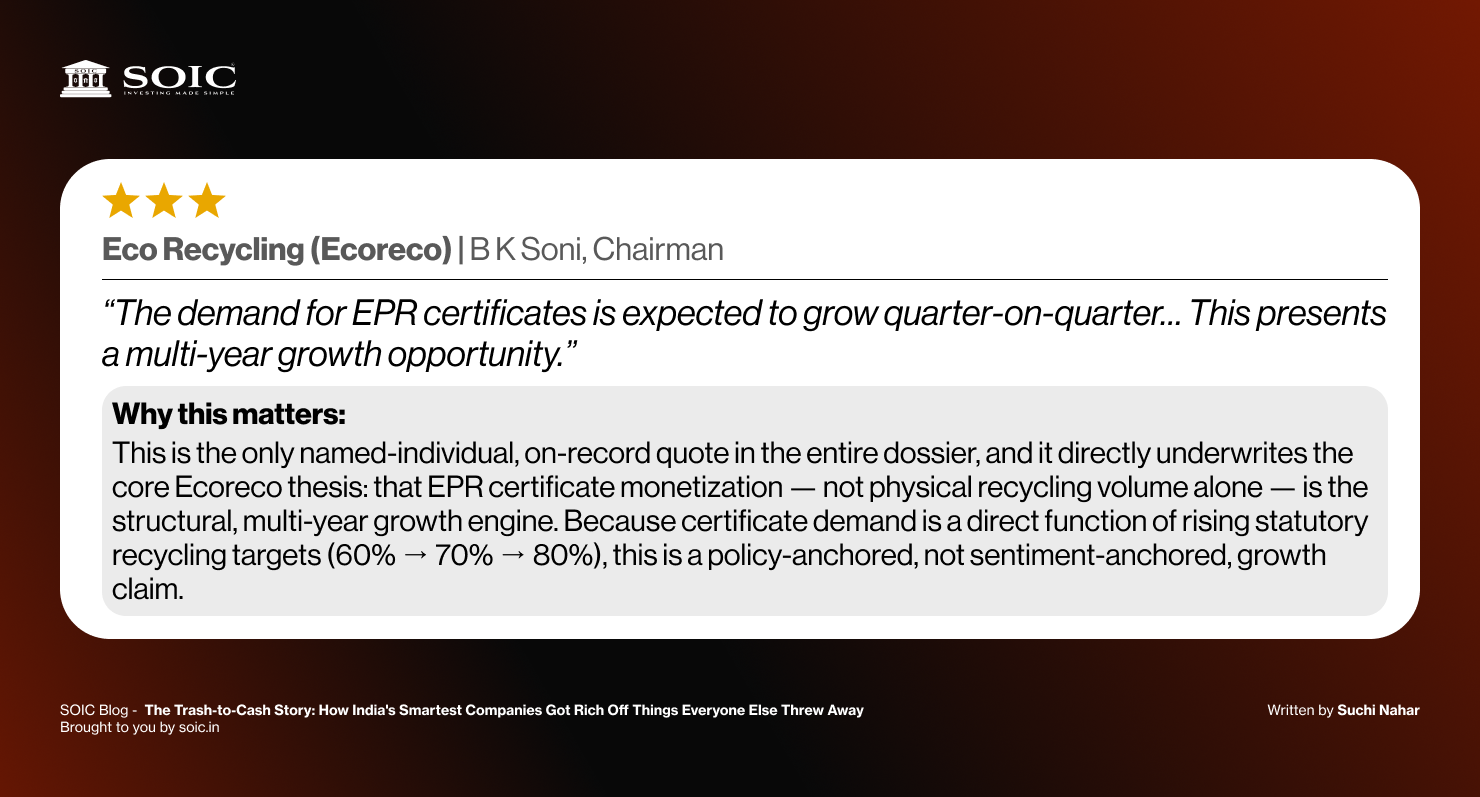
The regulatory-arbitrage businesses (Ganesha, the e-waste names, Praj) are more exposed to policy timing risk — a single delayed notification can defer a full quarter of demand, something that essentially never happens to a business like Fine Organics or Privi, whose demand is pulled by product performance rather than compliance deadlines.
If you wanted to build a single company from scratch to satisfy every clause of the waste-to-wealth framework, it might look a lot like Manorama Industries.
Manorama takes forest seeds that would otherwise fall to the ground and rot — sal, mango kernel, kokum, and mowrah collected by tribal communities across India, plus shea nuts sourced from West Africa — and processes them at its Raipur facility into Cocoa Butter Equivalents (CBE), stearin, and a widening range of specialty fats and butters used by chocolate, confectionery, and personal-care manufacturers. Even the de-oiled cake left over from extraction is sold into the cattle-feed market. Very little of the raw material goes to waste, and almost none of the finished product resembles a plain commodity oil.
Commodity to value-add: Forest seeds with essentially no organized market price are converted, through seed milling, solvent extraction, refining, fractionation, and blending, into branded specialty fats (the MILCOA range, including ES70, ES70M and ES70S) engineered to replicate cocoa butter's melting, snap, and mouthfeel characteristics. CBE and stearin together made up roughly 71% of FY26 revenue — a clear sign the mix has already shifted decisively toward the high-value end.
Stable margins: Despite processing an agricultural raw material with genuinely seasonal, weather-dependent availability, Manorama has held EBITDA margins in the mid-20s through periods of volatile input and freight costs — consistent with FY26's roughly 26% margin and a similar print in the first quarter of FY27. Management is explicit that pricing is set on a cost-plus-margin, application-specific basis, not mechanically linked to the cocoa commodity cycle. That single design choice is arguably the whole investment thesis in miniature.
B2B and sticky: Every customer relationship runs through a technical qualification cycle — plant audits, product trials, shelf-life and melt-point testing — that can take up to two years to complete. Once a chocolate maker has validated a specific fat's melt and snap behavior in its recipe, switching suppliers risks changing the finished product itself, which is a risk most global confectionery brands simply won't take for a marginal cost saving.
Market leadership: Only a handful of companies globally produce CBE at scale, and most of those are large multinationals working primarily with African shea. Manorama's specific edge is in sal- and mango-based variants, where India's uniquely large sal forests and a collection network built over years give it a raw-material advantage that can't be replicated quickly — and domestic regulation restricting CBE manufacturing to sal, mango, and kokum seeds adds a further layer of protection at home.
Export dominance: More than half of revenue is generated from exports, with customers including Ferrero, Mondelez, Mars, Hershey, Nestlé, and Barry Callebaut on the confectionery side, and The Body Shop, L'Oréal, and Lush in personal care. Notably, the Ferrero relationship reportedly predates the current corporate entity by decades — a level of customer tenure that is itself a strong proxy for switching-cost economics.
Beyond fitting the framework, Manorama has a reasonably visible near-term growth bridge. Fractionation capacity — the metric that matters most, since this is the stage where refined oils become CBE, stearin, and other specialty fats — has grown from roughly 15,000 tonnes per annum in FY22 to about 47,500–52,000 tonnes currently, and management has laid out a further ~₹460 crore capex program (spanning a new 75,000-tonne fractionation plant in India, new Cocoa Butter Alternative capacity, and a backward-integration facility in Burkina Faso) that could take total capacity to roughly 1,27,000 tonnes — nearly 2.5x today's base — by around FY28–29.
The Burkina Faso investment is worth separating out conceptually, because it's a different kind of value creation than the domestic capacity build: it's about moving processing closer to the raw material rather than shipping low-value shea nuts to India first, which management expects to improve freight economics, sourcing security, and traceability, with an estimated three-year payback once operational.
No framework fit removes execution risk, and a few things are genuinely worth tracking rather than assuming away:
Step back from any single company and the mechanism becomes clear. Commodities are, by definition, priced by the market and available to everyone — there's no durable edge in simply buying and reselling one. The edge lives entirely in what happens between the commodity and the customer: the process knowledge, the accreditation, the collection network, the formulation IP, the years of trust built with a handful of blue-chip buyers. That "in-between" layer is what allows a business to price on cost-plus rather than commodity-spread terms, which is the real source of margin stability — not luck, and not temporarily favorable input prices.
Export intensity matters here for a subtler reason than most investors give it credit for. Passing a global brand's supplier-qualification process is a costly, multi-year filter that weeds out anyone whose "value add" is really just a domestic regulatory arbitrage or a temporary cost advantage. A company that survives that filter and keeps its customers for decades — as with Manorama's Ferrero relationship, or Fine Organics' presence across global food and plastics majors — has effectively had its moat audited by the toughest possible judges: the customers who could switch, and don't.
When screening the listed universe for a business that might fit this pattern, five questions do most of the work:
A "yes" across most of these is a far better filter than simply noticing that a company "recycles" or "processes" something. The theme isn't really about waste at all — it's about who owns the value created in transforming something nobody wants into something nobody wants to be without.
Step back far enough, and every company in this story is really just answering the same question: who gets to own the value hiding in something everyone else has given up on?
A forest seed rotting on the ground, a dead car battery, a bottle in a landfill, a tyre nobody wants to touch again — none of these have a "market price" in any meaningful sense. Nobody's fighting over them. And that's exactly the point. The businesses that win this game aren't the ones with the fanciest factory or the flashiest pitch deck. They're the ones patient enough to build the boring stuff first — a network of tribal seed collectors, a fleet of scrap-yard relationships, a customer who's spent two years testing your product before trusting it in their recipe. That patience is the real moat. Nobody can buy their way past it with a bigger cheque.
It's worth remembering that this isn't a new story dressed up in new language. Long before "EPR" and "circular economy" were terms anyone used in a boardroom, a man was walking around with fat samples strapped to his own body, trying to convince a chocolate maker that what he'd ground out of forest seeds was worth something. He was right. Eighty years later, that same instinct — take what's cheap and overlooked, refine it patiently, sell it to someone who can't easily walk away — is still the surest way anyone in India has found to turn trash into wealth.
The regulations will keep changing. The commodity cycles will keep swinging. But that underlying idea won't go out of style — which is exactly why it's worth paying attention to who's actually building it, and who's just borrowing the story.
Disclaimer: The information provided is for educational purposes only and should not be considered investment advice. We are SEBI-registered research analysts.
We believe that investment decisions should be based on personal conviction and not borrowed from external sources. Therefore, we do not assume any liability or responsibility for any investment decisions made based on the information provided in this reference.


0 Comments